WHAT IS YOUR CREDIT SCORE?
When I have a conversation with a new client, one of the first questions I usually ask is: “How is your credit? Do you know what your credit score is?” Credit is an important part of qualifying for a mortgage. Your credit report contains valuable information about how you have managed your money over the years. It shows your borrowing history, payment patterns, outstanding balances, and other information that lenders use when evaluating a mortgage application.
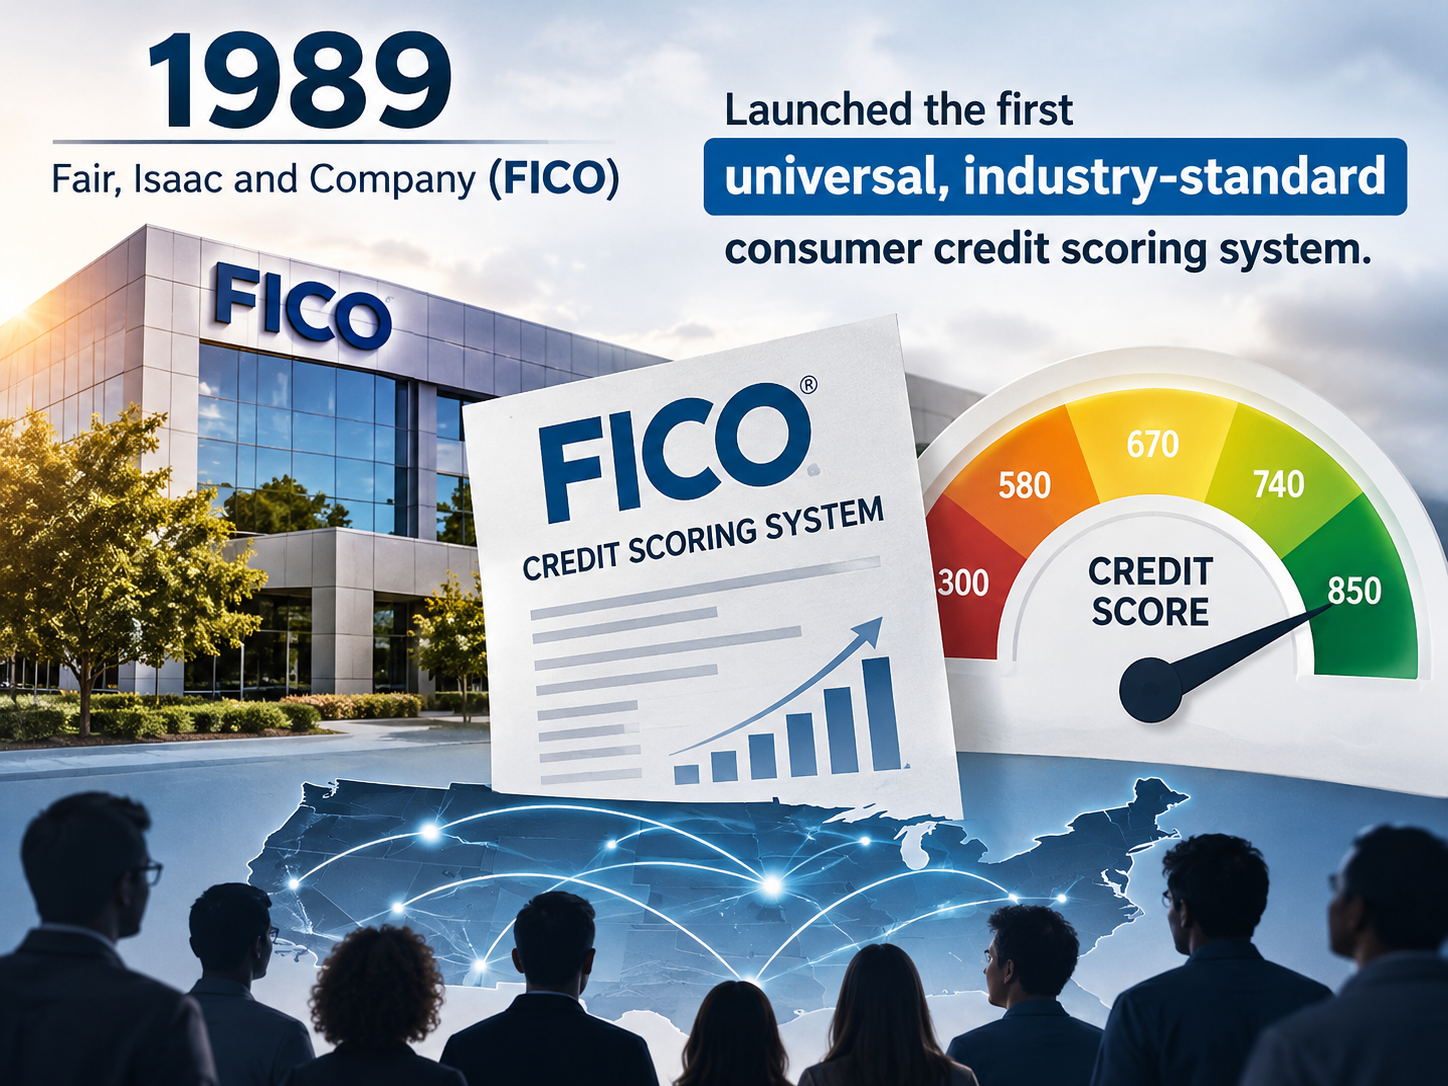
Years ago, the Fair Isaac Corporation developed a credit-scoring model that became known as the FICO score. The model uses information from credit reports to calculate a number that helps lenders evaluate the risk of lending money to a borrower.
Your credit score can affect whether you qualify for a mortgage, how much you can borrow, and the interest rate and other terms available to you. But here is something important: Your credit score is one part of your mortgage application that you may be able to improve.
I recently worked with a client whose credit score was around 680. If we could get it to 720, he might qualify for substantially better loan terms. I reviewed his credit report and recommended that he pay down the balances on most of his credit cards to approximately one-third of their limits. He followed my advice. But there was a problem. He continued using one of his credit cards for business expenses, and the balance climbed over its limit. When we checked his credit again, his score was still around 680. We were back where we started.
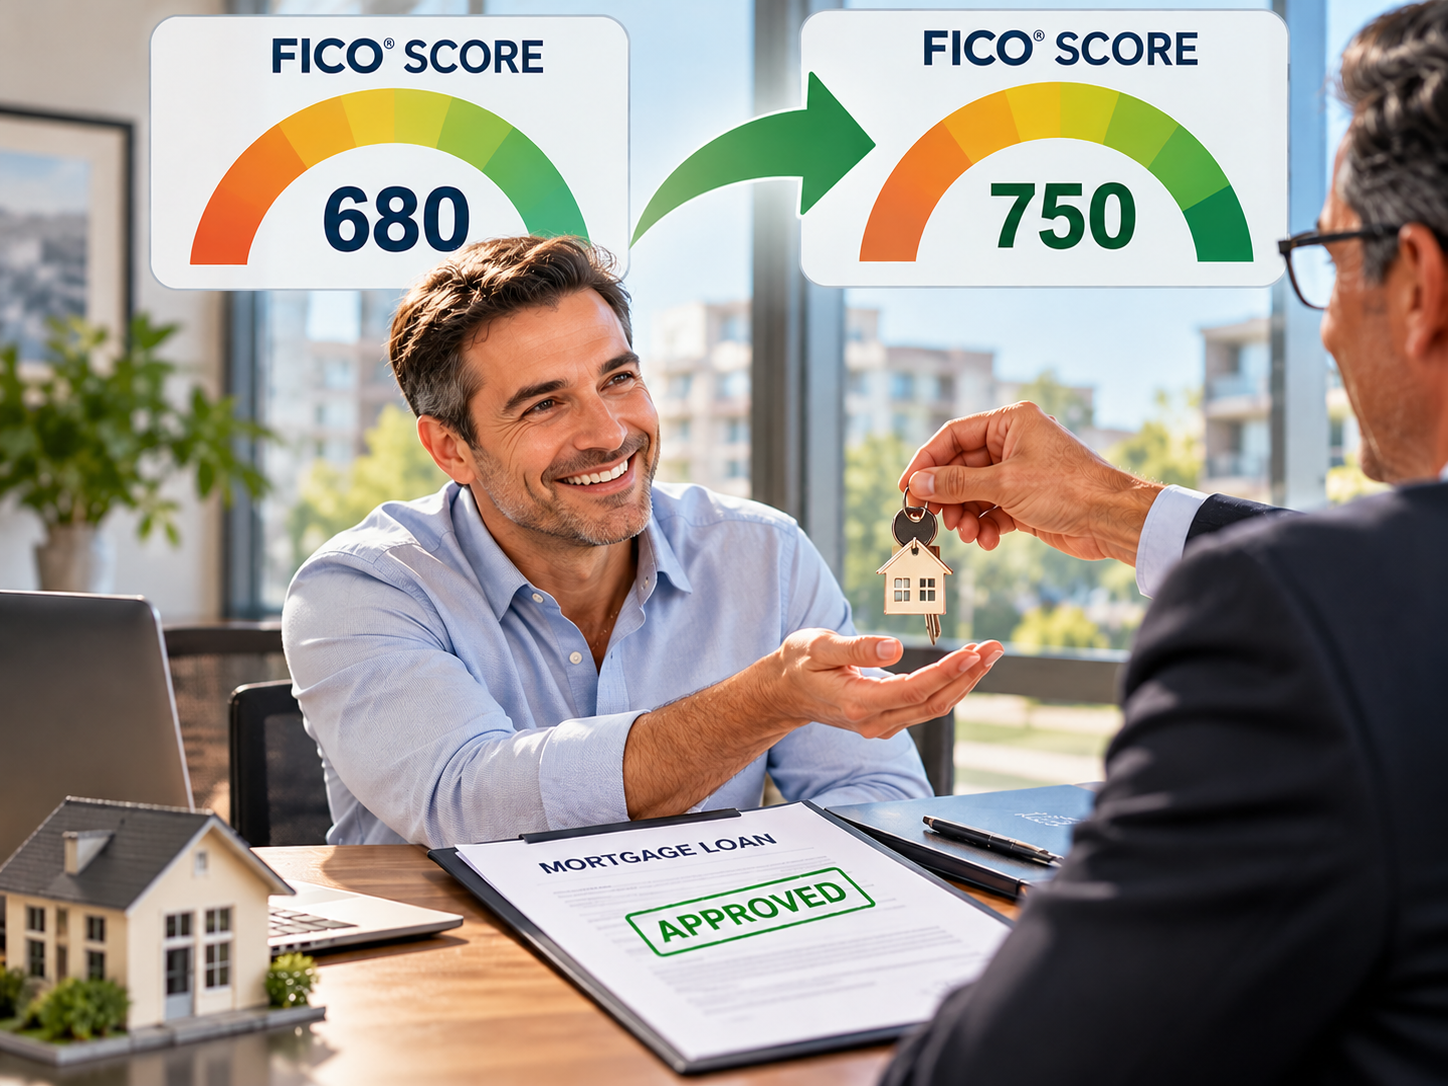
So, I suggested another approach. He had savings available, and I recommended that he consider using some of that money to pay down the balances on the credit cards appearing on his credit report. He did. The next time we checked, his score had increased to 750. That made a significant difference to our mortgage options.
There was one more challenge. Normally, when you pay down a credit card, the lower balance may not appear on your credit report until the creditor reports it during its regular reporting cycle. That can take several weeks. In this case, we used a process that allowed us to obtain updated credit information sooner. It involved an additional fee, but it helped us get the information we needed without waiting for the next regular reporting cycle. With the updated score, we were able to move forward and close the loan.
What is the lesson? First, don’t assume that the credit score you have today is the score you must live with forever. Second, don’t make large financial moves without understanding how they may affect your overall situation. Paying down credit cards can help, but the result depends on your entire credit profile, and using savings to do it may not always be the best choice.
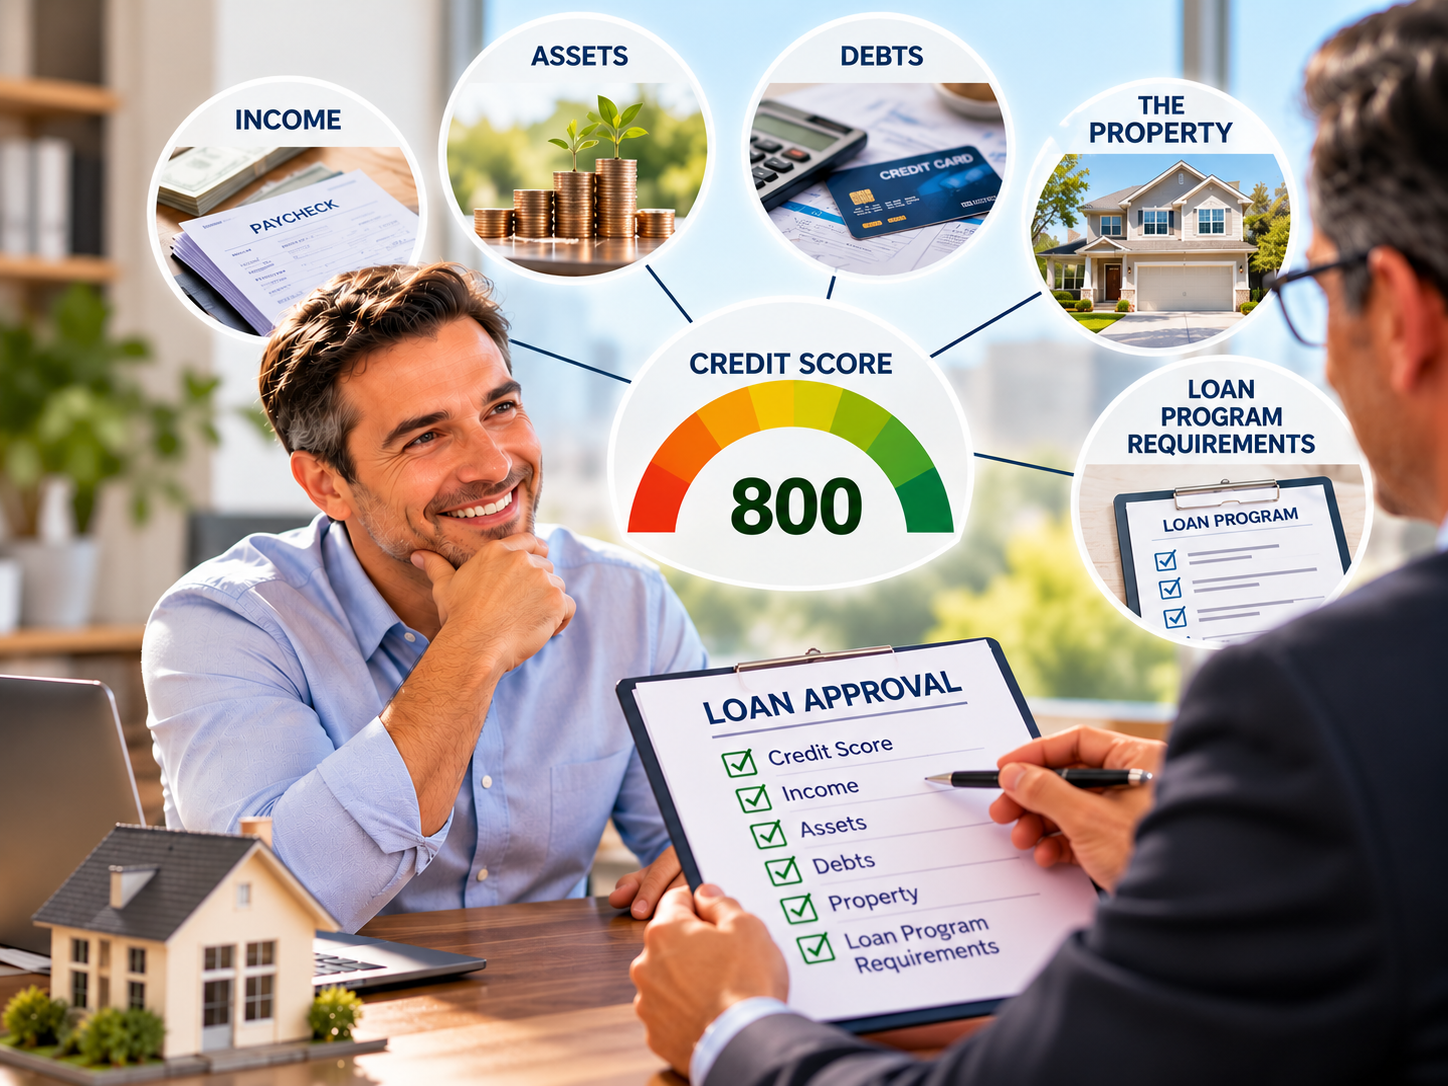
Third, if you are planning to buy a home or refinance, it can be helpful to review your credit well before applying. That gives you time to identify problems, correct errors, reduce balances when appropriate, and understand what may be possible. And remember: a higher credit score does not guarantee loan approval. Lenders also look at income, assets, debts, the property, and the requirements of the particular loan program.
After more than 40 years in the mortgage business, I have learned that preparing for a mortgage is often just as important as finding the right lender. So, the next time you call me about a mortgage, be ready for one of my first questions: “What does your credit score look like?”
Manny Kagan
Mortgage Broker | 40+ Years of Experience
(415) 225-7920