The Good News with Manny

HOW TO GET A LINE OF CREDIT
I remember that more than 30 years ago, getting a home equity line of credit was not something mortgage brokers could easily arrange for their clients. Although banks and Savings & Loans offered certain options, but we didn’t have access to those programs.

Then I became friendly with a bank manager who allowed us to offer his bank’s line of credit to our clients. It was a big deal! Finally, we had another way to help people who needed money without refinancing their existing first mortgage.

A lot has changed since then. Today, many banks are much more selective about offering lines of credit. Some prefer to work with their existing customers, especially those who maintain substantial deposits with the bank. Fortunately, mortgage brokers now have access to different sources of financing, although qualifying depends on each client’s circumstances.
Let me give you a few examples. Recently, I closed a second mortgage for a client who was doing major remodeling on his home. He needed approximately $500,000. He had approached his bank, but the bank turned him down. After reviewing his situation, I found a different solution: a reverse mortgage second. The lender offered him $600,000. I suggested that he consider taking the larger amount because, when you are doing construction, you never know what unexpected expenses may come up. Of course, the additional borrowing also has costs that need to be considered. We closed the loan.

Then I had another client who was going through a divorce. She wanted to keep her home but needed money to pay her husband his share of the equity. Once again, I was able to arrange a reverse mortgage second.

Reverse mortgages can be very helpful, but they are not for everyone. Right now, I am working with another client who needs a relatively small amount of money to finish one of his projects. He already has a first mortgage with a very low interest rate, and he doesn’t want to lose it. That makes sense. Why refinance an entire mortgage at a higher interest rate when you only need additional money? But there is a problem. His income is not sufficient to qualify for a conventional line of credit under the programs we have reviewed. So, I am looking at other possibilities, including a reverse mortgage, if he qualifies. In his situation, that might mean a loan rather than a traditional line of credit.

Another client wants to buy a business. Not a building. A business. She needs money for the purchase, and she has substantial equity in her home. I am exploring a loan program that may allow her to borrow against that equity without relying entirely on conventional income qualification. Again, a different situation requiring a different solution.
I regularly receive information about new home equity loans and lines of credit. Some of the offers look very attractive. But there is a difference between receiving an offer and qualifying for the loan. For a conventional line of credit, the lender generally has to consider your existing mortgage payment, property taxes, insurance, car payments, credit card obligations, and other debts. Then we add the payment on the proposed new loan. All of this has to be compared with your qualifying income. And that is where many borrowers run into problems. They may have substantial equity in their homes and excellent credit, but their reported income is not enough to qualify. That doesn’t necessarily mean there is no solution. It means we have to look at other options.

Sometimes it is a conventional home equity line of credit. Sometimes it is a fixed-rate second mortgage. Sometimes it is a reverse mortgage. And sometimes it is a specialized loan program that looks at the borrower’s financial situation differently. Every case is different.

After more than 40 years in the mortgage business, I have learned that the important question is not simply, “Can I get a line of credit?” The better question is: “What is the best way to get the money I need without disturbing the mortgage I already have?” That is where experience and knowing the available programs can make a difference.

So, if you have a good first mortgage with a low interest rate and need some additional money, give me a call. I might be able to help you find a solution.

Thank you!

Manny Kagan
Mortgage Broker | 40+ Years of Experience
(415) 225-7920

Fridays with Manny

image

DO YOU LOVE YOURSELF?

Many years ago, at the start of my career as a mortgage broker, I worked with several business coaches. One of them was Tom Hopkins, a well-known sales trainer. I still remember one of his suggestions. He encouraged us to start every morning by standing in front of a mirror, looking ourselves in the eyes, and repeating: “I love myself. I love myself.”

The reason for this simple exercise is quite profound. When you start your day with love toward yourself, you become more capable of sharing love with others. And when you approach life with love, you create an opportunity to experience something I wrote about last week: feeling good.

Think about it. How can we genuinely love others if we do not first learn to love ourselves? Interestingly, this idea is thousands of years old. In the Torah, we find the commandment:

“Love your neighbor as yourself.” (Leviticus 19:18)

The same teaching appears in the New Testament, where Jesus repeats this commandment and emphasizes its importance, saying, “There is no commandment greater than these.” (Mark 12:31)

Similar teachings about love, compassion, and caring for others can also be found in Islam. Isn’t it remarkable that different religious traditions share such a simple and powerful message?

But there is something else worth considering. The commandment tells us to love our neighbors as ourselves. This suggests that loving ourselves is an important part of learning how to love others. And loving yourself does not mean being selfish or thinking that you are better than anyone else. It means accepting yourself, appreciating who you are, and treating yourself with the same kindness and respect you would offer someone you love.

So, what do we need to do? Tomorrow morning, when you get up, stand in front of your mirror, look yourself in the eyes, and say: “I love myself. I love myself.” Try doing this every morning. Give yourself some time, and I believe you might be surprised by the results.

Why am I bringing this to your attention? Because I have practiced this simple philosophy for many years, and I believe it has helped me live a less stressful, more enjoyable life.

Of course, life brings challenges. We cannot control everything that happens around us. But we can influence how we respond to those challenges and how we feel about ourselves. As I often say, “I’m always good, and tomorrow I’m going to be even better.”

And it all begins with how we treat ourselves. After all, isn’t that what we all want—to feel good? Perhaps the first step is much simpler than we think. Just look in the mirror and say: “I love myself.”

And don’t forget to smile. The person looking back at you deserves your love, too.

Love and beauty go hand in hand. That is why I am sharing with you three beautiful flowers. You can find many more of these wonderful creations of nature in my book Reflections: The Healing Images.

Feel good, love yourself, and enjoy the beauty that surrounds you!

image

The Good News with Manny

HOW TO STOP FORECLOSURE

Foreclosure happens when borrowers stop making their monthly mortgage payments to the bank or lender that provided the loan secured by their property. You might be surprised to learn that foreclosure can happen to the most unexpected people, even those who have substantial equity in their homes. Let me share a recent experience.

In 2001, I helped a woman whose husband had just passed away refinance the mortgage on her home into her name. In 2007, I refinanced her mortgage again and arranged a home equity line of credit because she needed additional funds. Her only sources of income were Social Security and rent she received from renting rooms in her house. Together, they provided enough money to cover her monthly mortgage obligations. Everything seemed to be working well until a few months ago, when I received a phone call from her daughter.

The daughter’s family was now living in the house. Unfortunately, while the family was between jobs, the mortgage payments stopped. After several months without payments, the lender issued a Notice of Default (NOD), and the property was facing foreclosure. Imagine the situation. The house was worth approximately $4 million, yet the family was at risk of losing it because they could not keep up with the mortgage payments. To make matters worse, the mother’s credit score had dropped to 570, making conventional refinancing extremely difficult.


But as I always say, there is almost always a solution. We just need to find it.
After exploring the available options, I was able to arrange an equity utilization loan, better known as a Reverse Mortgage. One of the important benefits of a Reverse Mortgage is that borrowers are not required to make monthly principal and interest payments. They must, however, continue paying property taxes, homeowners’ insurance, and other property-related obligations, and meet the loan’s occupancy and maintenance requirements. This solution allowed us to address the outstanding mortgage obligations and stop the foreclosure process, protecting the family’s substantial home equity.

But there was another important part of this story. The daughter had a properly prepared Specific Power of Attorney, allowing her to act on her mother’s behalf. The property was also held in a trust. These documents played an important role in allowing us to move forward with the transaction.

And this brings me to my realization. Planning ahead can make the difference between protecting your home and potentially losing it. Many people believe that estate planning is only about what happens after we pass away. In reality, properly prepared legal documents can be just as important while we are alive, especially when unexpected circumstances arise.

My message to all of you is simple. Make sure you have an appropriate trust and power of attorney prepared by qualified professionals. These documents must be designed for your particular circumstances, and not every power of attorney or trust automatically authorizes a mortgage transaction. If you do not have these documents, or if they have not been reviewed for many years, now might be a good time to take action.

And if you or someone you know is having difficulty making mortgage payments or is facing foreclosure, do not wait until the last moment. The sooner we explore the possibilities, the more options we may have. Feel free to reach out to me if you need mortgage assistance or recommendations for qualified estate planning professionals.

Remember, your home equity represents years of hard work. Protecting it is worth the effort.

Manny Kagan
Mortgage Broker | 40+ Years of Experience
(415) 225-7920
Fridays with Manny

image

HOW TO FEEL GOOD

– How are you?
– Always Good! – This is almost always my answer to the question. It has become my trademark. Somebody once suggested that saying “good” all the time might be limiting, so I added something to my response: “I’m always good, and tomorrow I’m going to be even better!”

What does it mean? It means that I try to live according to my outlook on life: whatever happens, I look for the good in it. This is how I choose to live. Of course, not everyone can adopt this philosophy. We all have different circumstances, different challenges, and different views of life. We are surrounded by distractions, and sometimes it is difficult to avoid being affected by what happens around us. But over the years, I have learned an important lesson. Recently, my six-year-old granddaughter reminded me of it in a way I will never forget.

I Want to Feel Good!

Last April, my granddaughter visited us from Portland, Oregon, where she lives with her parents, my daughter and her husband. We took the family to some of our favorite places, where we often spend time walking with Max, our dog. One of those places is Ocean Beach. My granddaughter loved it! She ran into the water, splashed around played in the sand, and had a wonderful time. Naturally, she got wet and dirty.

Her mother became upset and raised her voice, wanting her to change her skirt. But my granddaughter refused. She loved that skirt! And then she said something that stayed with me: “I love this skirt. I want to feel good!”

She kept repeating: “I want to feel good! I want to feel good!” Those words got stuck in my mind. There was something so simple and honest about what she was saying. She wanted to enjoy herself. She wanted to feel good. And she didn’t want to give up something she loved just because the situation wasn’t perfect.

Her words reminded me of my own philosophy. But they also inspired me to put that philosophy into a simple mantra. I even recorded a YouTube video in which I share this idea. The original version went like this:

  • If, whatever it is, doesn’t make me feel good, I’m not interested.
  • If, whatever it is, doesn’t help my loved ones feel good, I’m not interested.
  • And if I cannot do anything about it, I’m not interested.

The idea is simple: why spend our precious time and energy on things that make us feel bad, especially when there’s nothing we can do to change them?

What Does Feeling Good Mean to Me?

I feel good most of the time. Of course, I don’t feel good every minute of every day. Nobody does. But feeling good doesn’t mean being happy all the time or pretending that problems don’t exist. It means appreciating the things that make life worthwhile.

When I help a client close a mortgage loan, I feel good. When I receive the commission for that loan, I feel good, too. Why? Because that money allows me to pay our employees, and that makes me feel good. When my wife and I travel together, I feel good. This December, we are planning a ten-day trip to Kauai, and I already feel good about it.

There are so many things in life that can make us feel good. We just have to recognize them and appreciate them.

I have also learned to pay attention to what I allow into my life. I don’t watch television, and I don’t read the daily news. I have found that much of what I would encounter there doesn’t make me feel good. Instead, it can create unnecessary worry, frustration, or negativity and take time away from the things I enjoy.

This is my personal choice. I would rather spend that time walking with Max, being with my wife, helping my clients, learning something new, working on my next book, or simply enjoying the world around me.

Life is too precious to spend all our time worrying about things we cannot change.

A More Positive Mantra

Recently, I started thinking about my original mantra.

Although it expresses what I believe, I wondered whether it sounded too negative. It focused on what I wasn’t interested in rather than on what I wanted to embrace. So, I decided to turn it around.

Here is my new version:

  • If it makes me feel good, I’m interested.
  • If it makes my loved ones feel good, I’m interested.
  • If I can do something to make myself or someone I love feel good, I’m interested.

And if I cannot change it, I’m not interested. Otherwise, I don’t want to spend my time and energy on it. I like this version better because it focuses on the positive. It encourages me to look for opportunities to feel good and to help the people I love feel good, too. And if there is a problem, I cannot do anything about, I try not to let it take over my life.

Of course, there are responsibilities we cannot ignore and problems we must face. Feeling good doesn’t mean running away from them. Sometimes, taking care of a difficult situation is precisely what makes us feel good afterward.

If you would like to start feeling good, order three of my latest books on Amazon.

Thank you!

image

The Good News with Manny

A SIGH OF RELIEF
Part Two

Last week, I shared some of the challenges I faced while helping a client obtain a mortgage so she could pay her sister her share of their father’s inheritance. We had already overcome several obstacles, but the real kicker was still ahead.

After finding a way to obtain a smaller loan, I had to find a way to get my client a much larger amount of money. We needed a loan program that would not require her to provide tax returns. Fortunately, my client had just turned 62. That opened another possibility: a reverse mortgage.

Reverse mortgages are available to eligible borrowers starting at age 55 under some programs, although the age requirements depend on the type of loan. With reverse mortgages, the older the borrower, the more money may be available, subject to the property’s value and other requirements.

Because the property had a high value, we needed two appraisal reports. The results were surprising. One appraisal showed a much higher value than the other. Unfortunately, the lender had to use the lower of the two values. Fortunately, even the lower value gave us enough equity to obtain the money my client needed. I thought we were finally getting close.

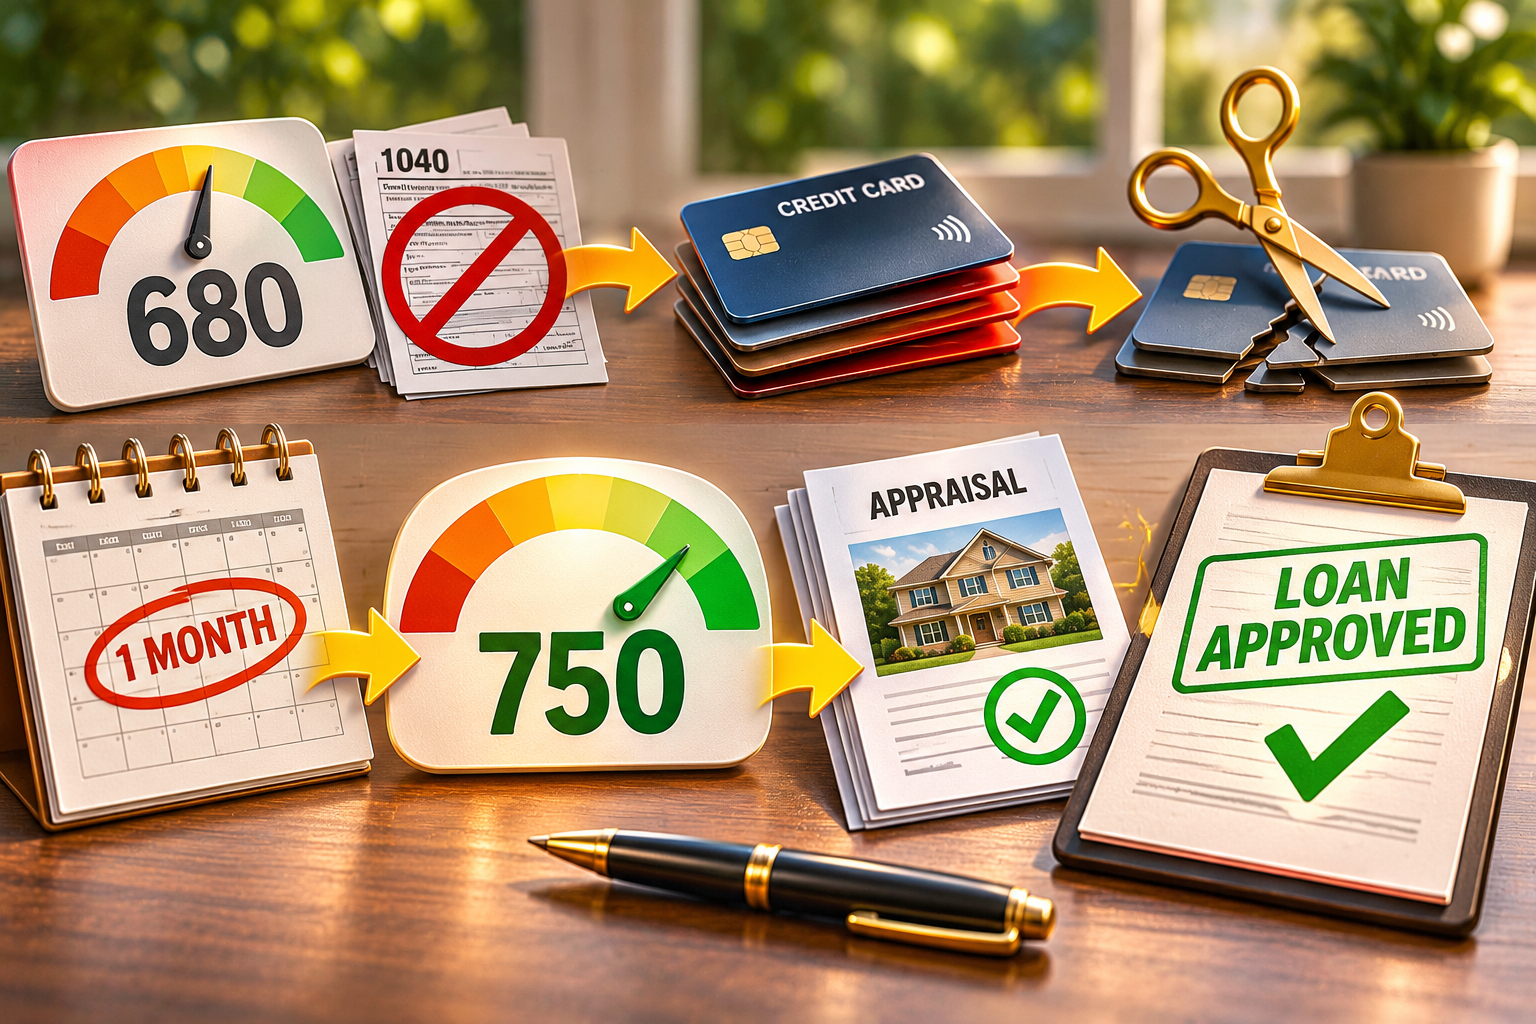
Then another unexpected condition appeared. My client’s credit score was around 680, and the lender required tax returns. But my client hadn’t filed them. I had never encountered this particular situation before. So, I decided to submit the loan to another lender.

There is a saying often attributed to Albert Einstein that the definition of insanity is doing the same thing over and over again and expecting different results. Perhaps I was doing exactly that. But the new lender looked at the situation differently.

The lender told me that if we could get my client’s credit score to 720 or higher, tax returns would not be required under that particular loan program. Now we had another possible solution. I suggested that my client use some of the money she had received from the first refinancing to pay off her credit card balances. She did.

About a month later, we checked her credit again. Her score had increased to 750. That changed everything. We were able to transfer the appraisal reports to the new lender, and the loan was approved.

Of course, we still had some title-related issues to resolve, and we were running out of time. But we kept going. Finally, last week, I received my commission check. My wife, Elpha, and I have worked together for more than 40 years. When she saw the check, she said something that made me smile: “Now you can say that the deal is closed.” And she was right. What a relief!

Looking back, this double transaction taught me something important. When you begin working on a complicated mortgage, you cannot predict every obstacle you will encounter. Sometimes, you don’t discover a problem until you have completed several steps.

And sometimes, a solution that seems impossible at first becomes possible when you look at the situation from a different angle.

  • You have to be patient.
  • You have to know your options.
  • And you have to be willing to keep looking when the first answer is no.

This is true in the mortgage business, and I believe it is true in life. After more than 40 years in the mortgage business, I still learn something from every complicated transaction. And that is one reason I enjoy what I do.

There are many people out there who are struggling with financial problems and don’t know where to turn. Some may need help with a mortgage. Others may need someone to explain their options and help them understand what is possible.

So please don’t be shy about reaching out to people who might need help. Sometimes, all it takes is a conversation to discover a possibility they didn’t know existed. Where there is a will, there is a way.

Thank you for following my story!

Manny Kagan
Mortgage Broker | 40+ Years of Experience
(415) 225-7920
Fridays with Manny

image

WHY SKELETONS ON HALLOWEEN?

The ancient Celtic tradition

Halloween has roots in the ancient Celtic festival of Samhain, celebrated around the end of October. People believed that during this time, the boundary between the world of the living and the world of the dead became less distinct. Fire, costumes, and rituals were associated with protecting people from harmful spirits.

The Christian tradition of remembering the dead

November 1 became All Saints’ Day in the Christian calendar, followed by All Souls’ Day on November 2 in many Christian traditions. The preceding evening became known as All Hallows’ Eve, eventually shortened to Halloween.

Skeletons and skulls became symbols associated with death and the temporary nature of human life. In medieval Europe, artistic images called danse macabre, or the Dance of Death, reminded people that death comes to everyone, regardless of wealth or social position.

Why skeletons became popular decorations?

Over time, Halloween developed into a holiday of costumes, frightening characters, and playful encounters with the supernatural. Skeletons became ideal decorations because they are instantly recognizable, easy to manufacture, and can be arranged in funny or frightening scenes.

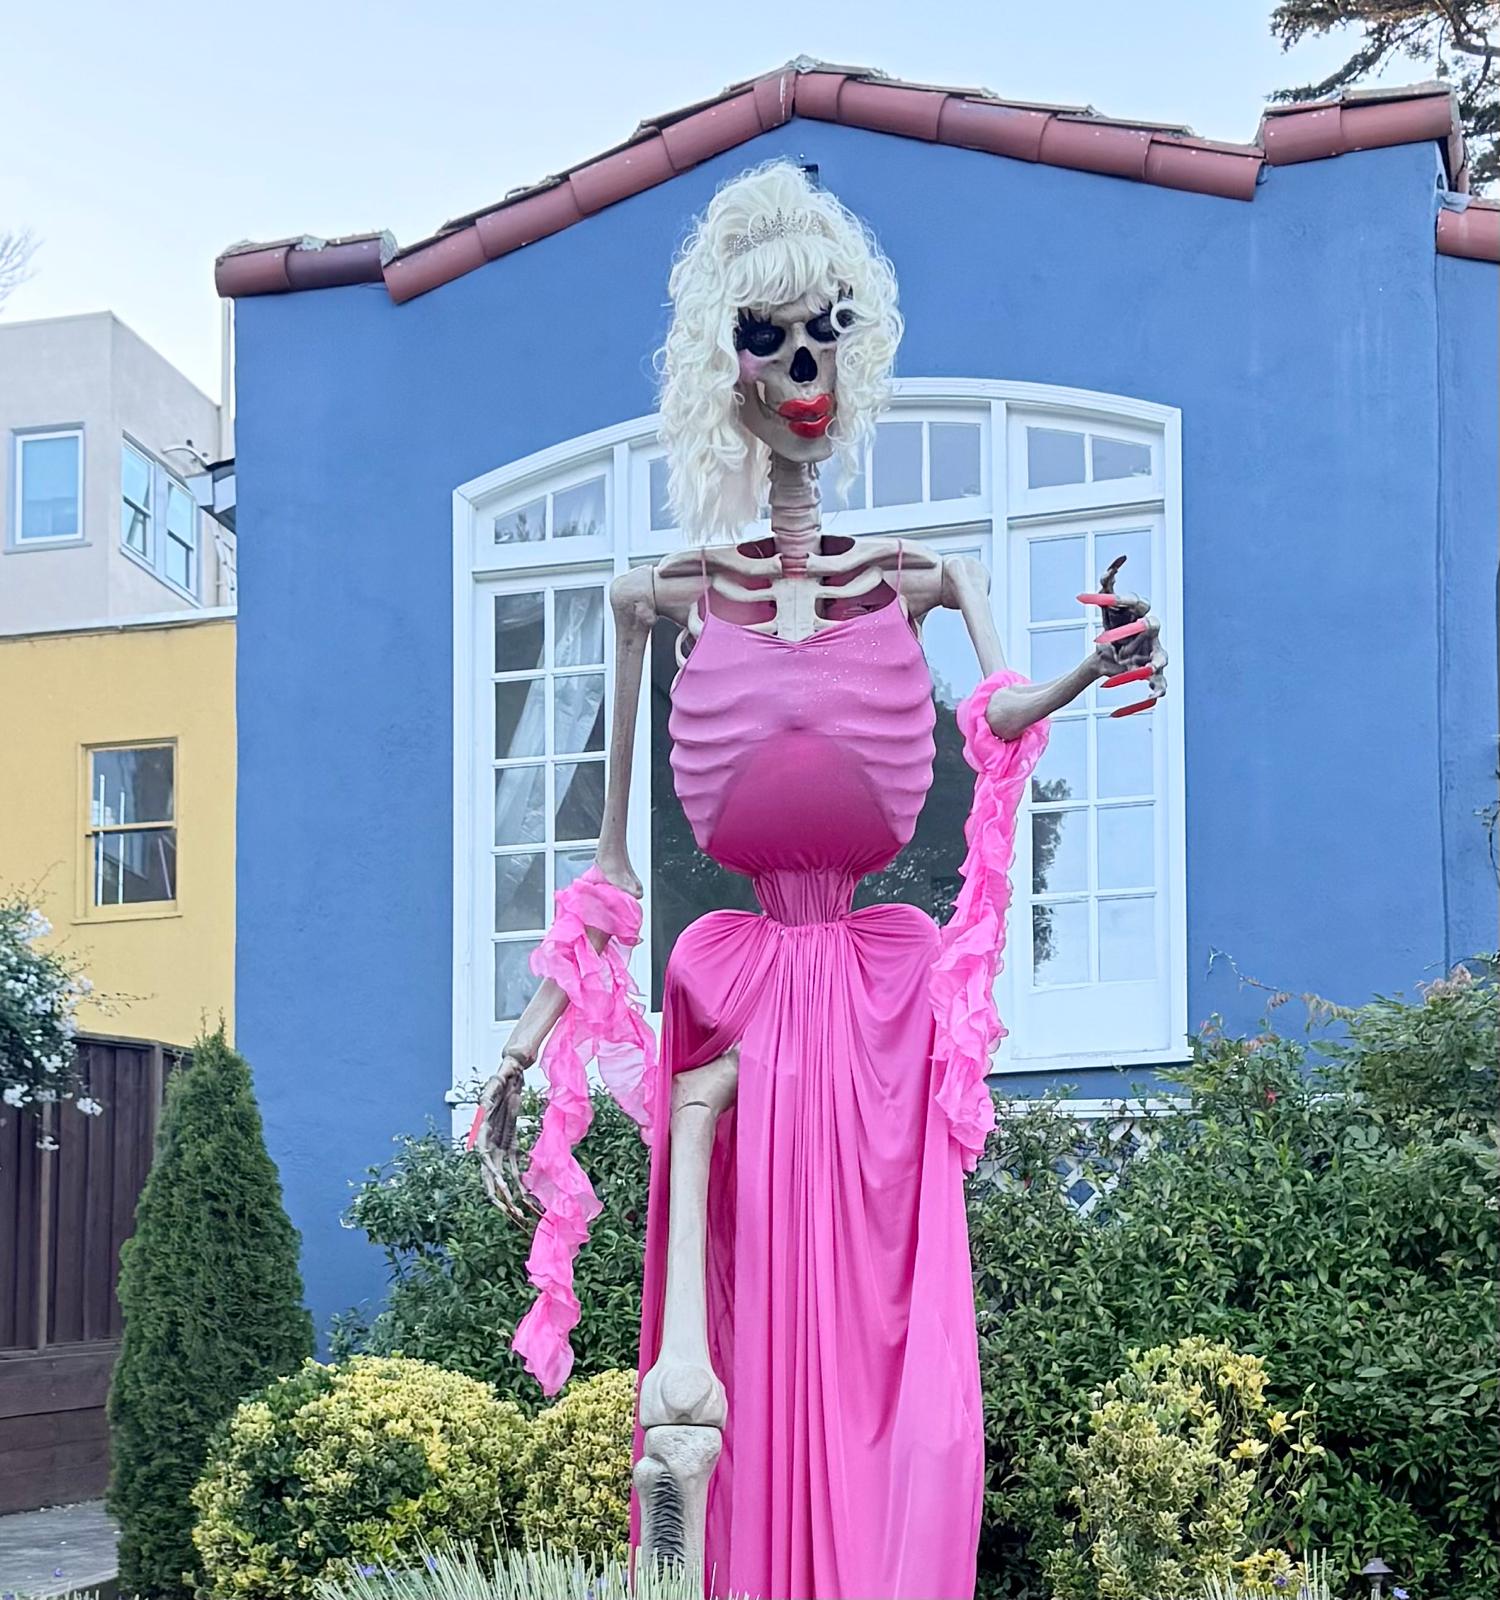
Today, homeowners place skeletons on their porches, hang them from trees, or arrange them as if they were having a party. What once symbolized death can now be a source of humor and creativity.

And what does it mean today?

For most people, skeletons are no longer a serious reminder of death or a representation of ancient beliefs. They are simply part of the fun of Halloween.

There is an interesting contrast here: skeletons represent the end of life, yet people use them to celebrate, laugh, and bring their neighborhoods together.

Perhaps that is one of the reasons Halloween decorations have become so creative. People can take something that might otherwise frighten them and turn it into something amusing.

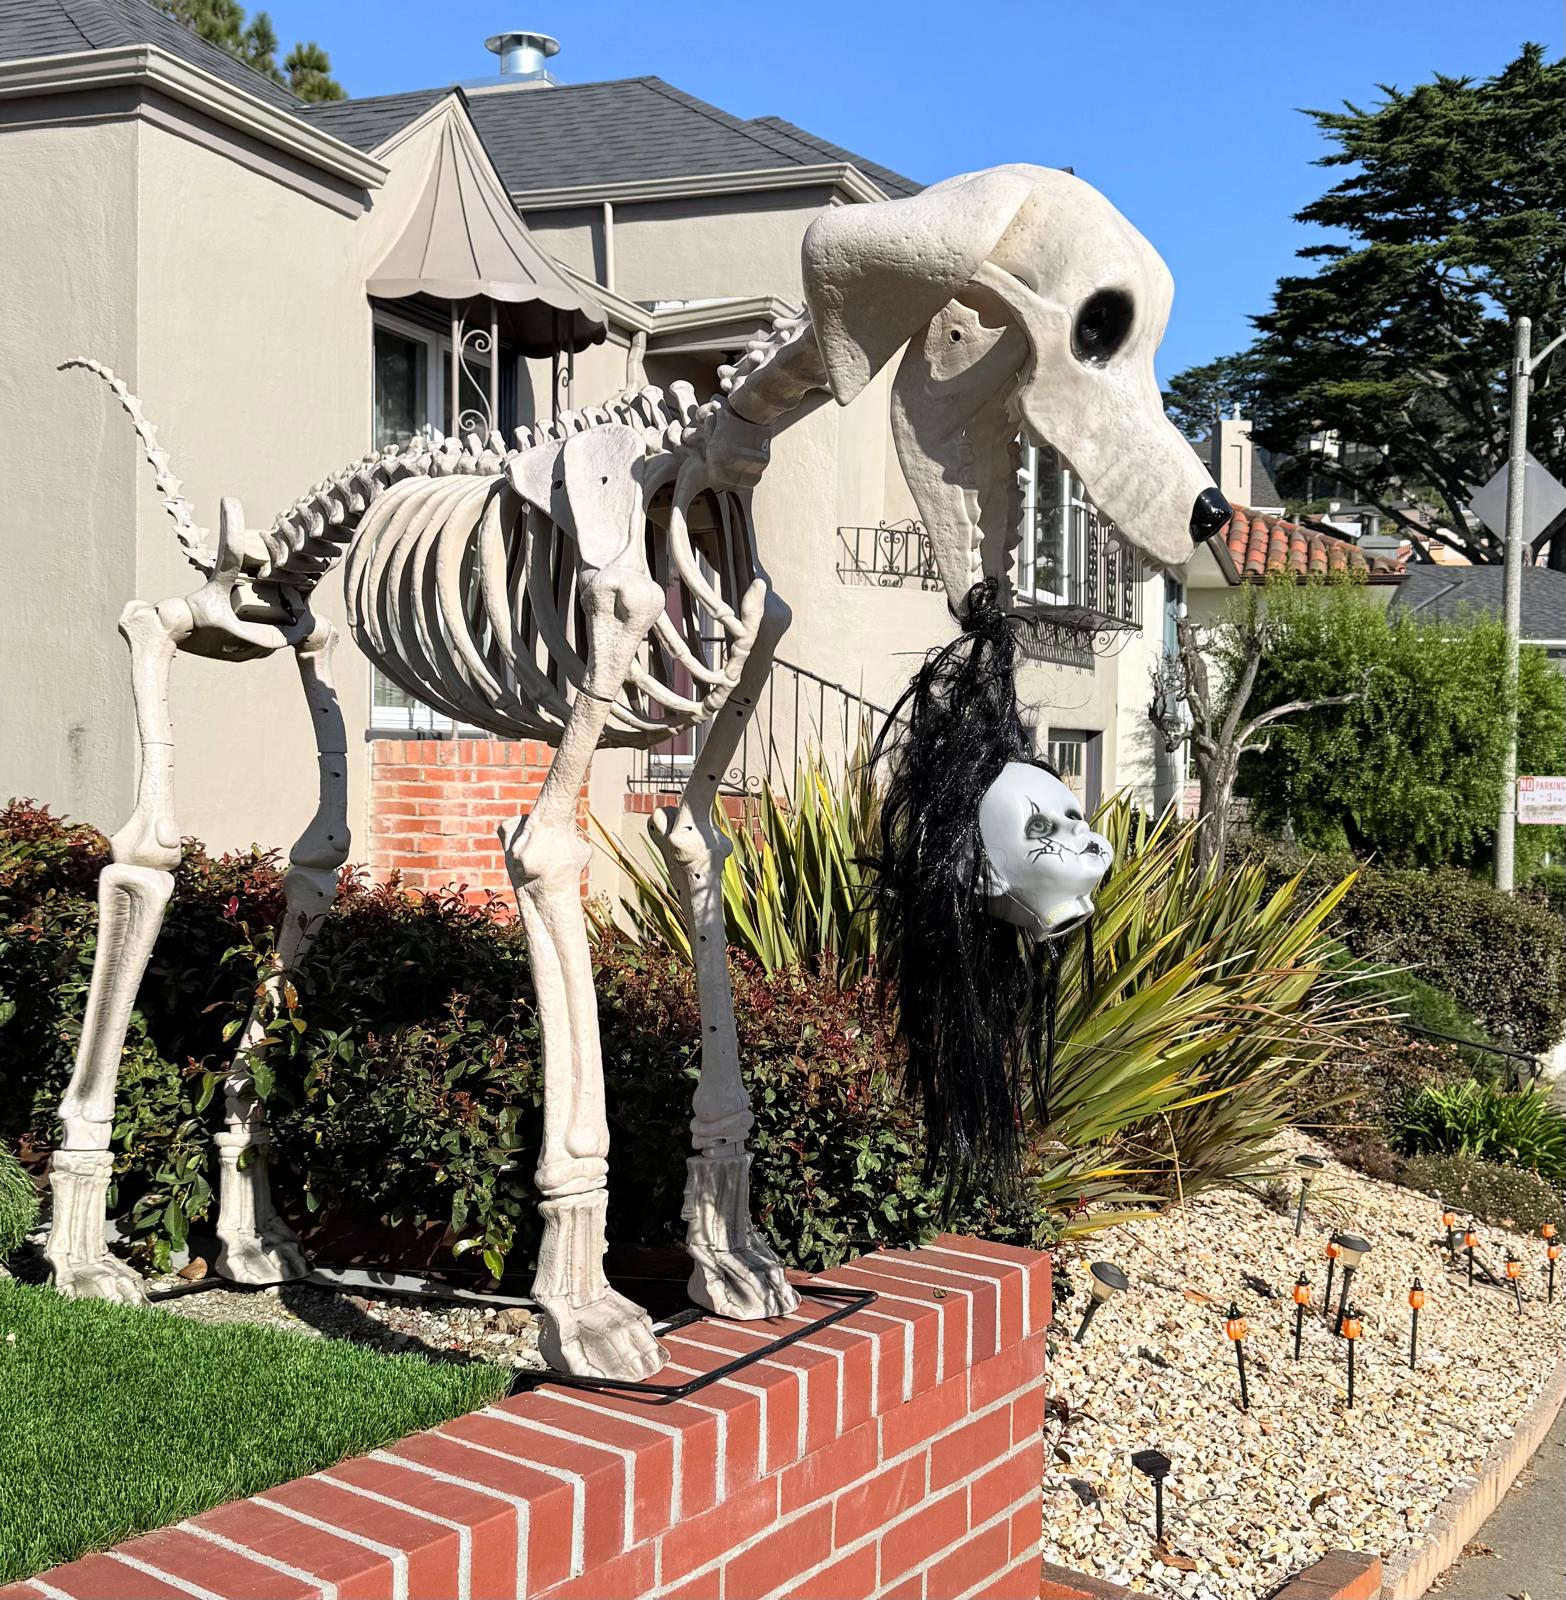
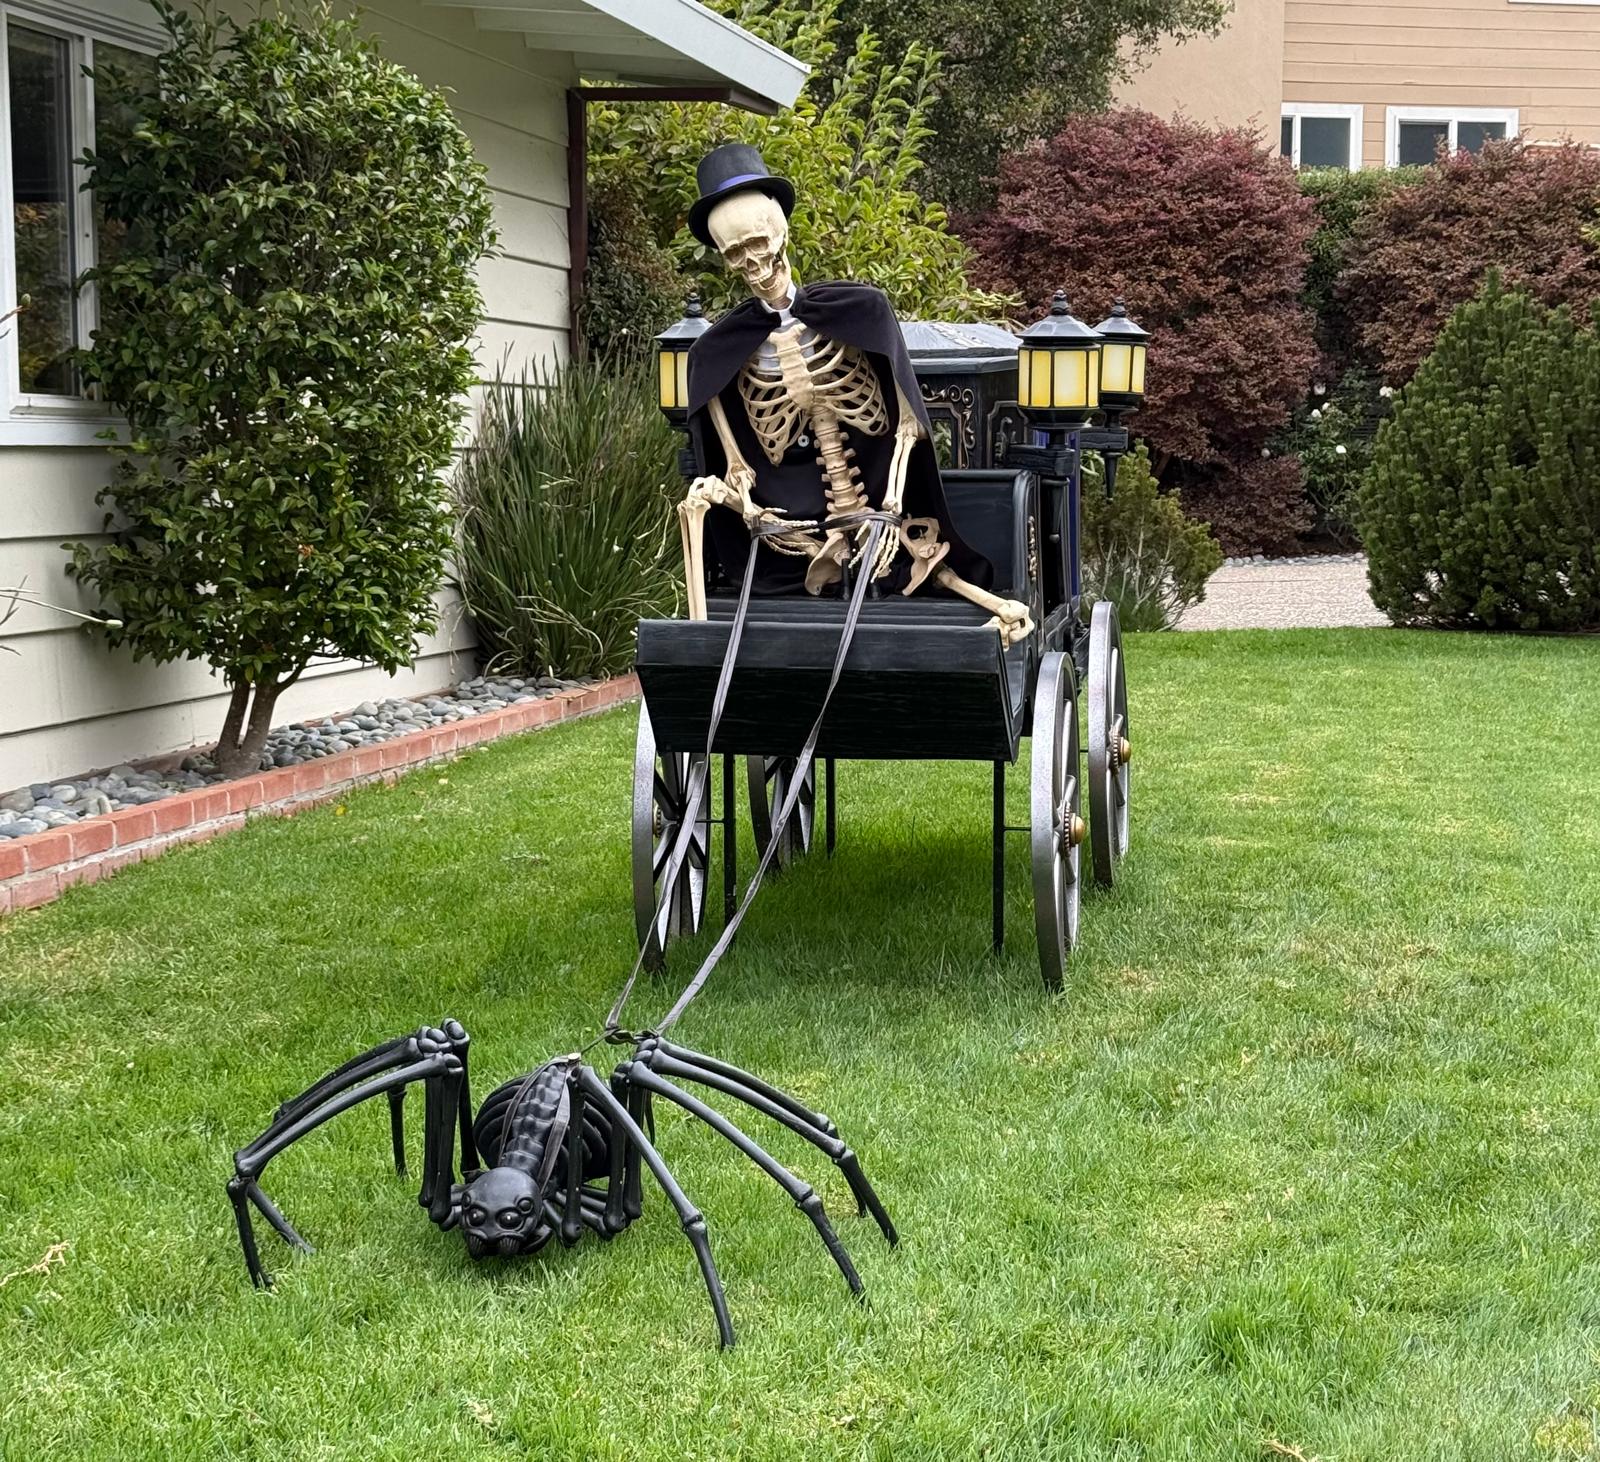
And as you have observed in your neighborhood, some homeowners turn their front yards into elaborate scenes, using skeletons as characters in their own little stories, as you can see in the three images above.

Enjoy and share!

image

The Good News with Manny

A SIGH OF RELIEF

Part One

Yesterday, I breathed a sigh of relief. A loan transaction I had been working on for quite a while finally was approved. Here’s the story.

My client had inherited her late father’s house together with her sister. She wanted to keep the house and live there, while her sister wanted to sell it and divide the proceeds. It sounds simple, doesn’t it? It wasn’t. It took three attorneys, two appraisers, a real estate agent, and a judge to determine the amount that had to be paid to settle the matter. And then I came into the picture.

My client was working, but she did not have enough reported income to qualify for a conventional mortgage. She also had not filed her tax returns. Yet she needed a substantial amount of money to keep her father’s house and settle the matter with her sister. Where could we find the money?

I started by looking at her current home in Southern California, where she was living. There was only a small mortgage on that property. But there was a problem. To access the equity through the financing option I was considering, she needed to establish the inherited property as her new residence.

That meant moving out of her current home, finding a tenant, and establishing her new residence at her late father’s house. We needed to document the change with the appropriate records, including her driver’s license, bank statements, and bills.

There was another complication: the backyard at the house in Southern California was undergoing major repairs. We had to wait until the work was completed before moving forward with the next steps.

First, I found an experienced lender offering a good interest rate. We planned to use a special loan program designed for investment properties. Instead of relying on the borrower’s personal income, this type of program can qualify a loan primarily on the property’s rental income, subject to the lender’s requirements. The rental income could be supported by a special report prepared by the appraiser. The borrower also needed to demonstrate that she had sufficient reserves. We thought we were on our way.

Then the appraisal came. The appraised value was too low, which meant we could not obtain the amount of money my client needed. I reviewed the report with the lender, and we discovered several mistakes.

Fortunately, I was working with an experienced lender who knew how to handle the situation. The lender was able to order another appraisal, and the new report eventually provided the value we needed. One problem solved.

Then came the preliminary title report. It showed an old loan that supposedly remained unpaid, even though it had been paid off about 25 years earlier. Fortunately, the person associated with that old obligation was still alive and could confirm that there was no outstanding debt. But we weren’t finished.

The title report also showed tax liens dating back to an earlier period. Time was running short, so my client agreed to pay them off from the proceeds of the new loan and deal with the government afterward. Step by step, we worked through the obstacles.

Finally, the loan closed. My client had the money in her bank account to settle the matter and move forward with her life. But when we looked at the bigger picture, something else became clear. We had accomplished what she needed to do, but the financial consequences were substantial.

That is where I will leave you until next week. In Part Two, I’ll tell you more about what happened and what this transaction taught me about the mortgage business.

With more than 40 years of running my mortgage brokerage practice, I have learned that closing a loan is sometimes much more than just finding the right lender. It requires patience, experience, persistence, and the ability to solve one problem after another. And sometimes, when the loan finally closes, the biggest feeling isn’t excitement. It’s relief.

Meanwhile, if you know someone who might benefit from my mortgage services, please don’t hesitate to share my information with them.

Thank you!

Manny Kagan
Mortgage Broker | 40+ Years of Experience
(415) 225-7920
Fridays with Manny

image

HOW I CHOSE A NEW CAR

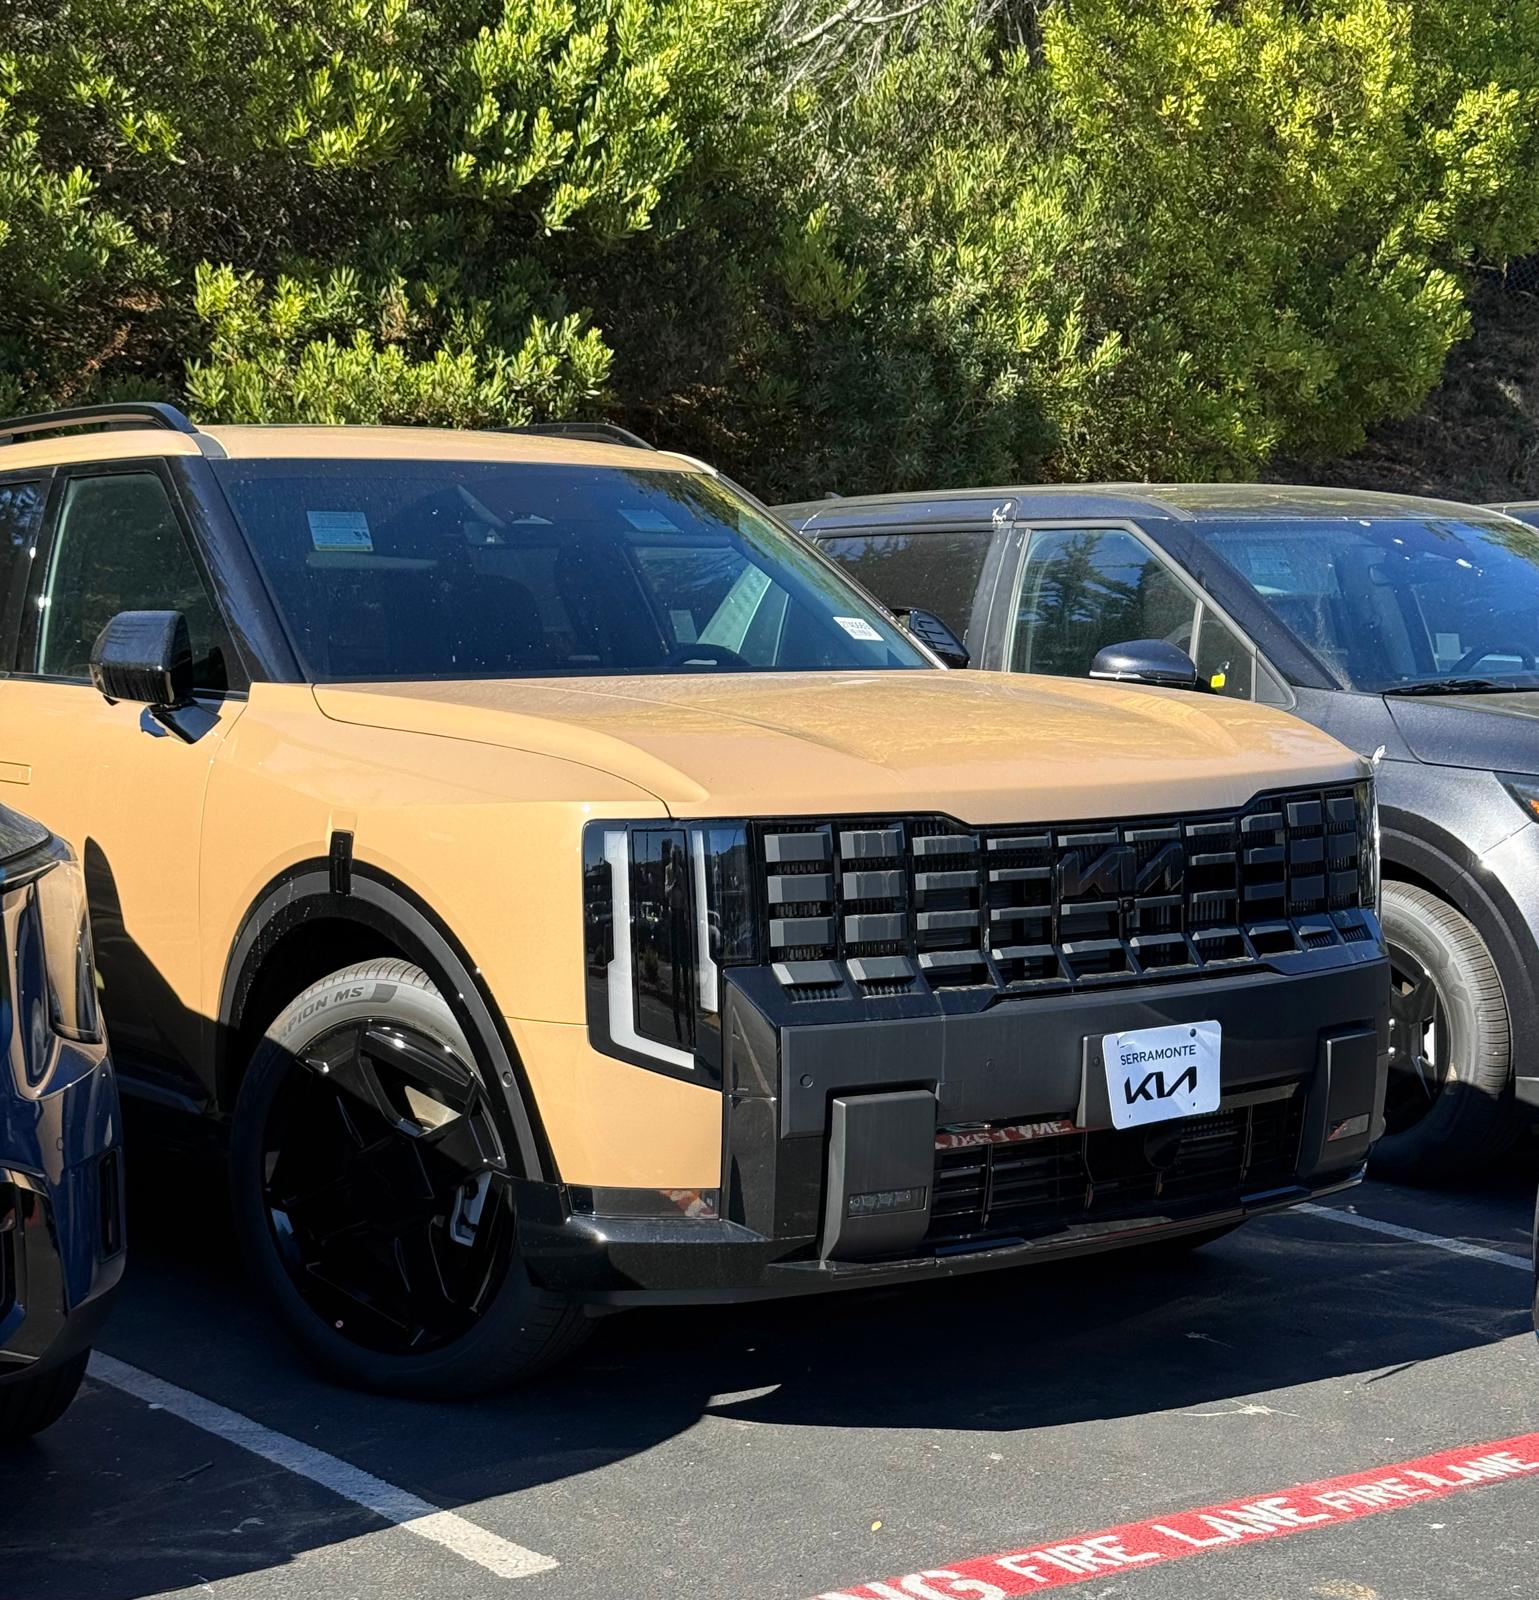
Have you noticed that our streets are becoming more colorful? I decided to join this movement!

The lease on my Audi Q5 was coming to an end, and I had to make a decision. The natural choice would have been to lease another Audi Q5, which would cost about $56,000 before taxes, or keep my existing car, which has only 27,000 miles, and finance the remaining $32,000 through a bank at 5.375% interest over five years. But I started thinking: During the next five years, anything could happen to the car. If something went wrong, I would have to pay for the repairs out of my own pocket. That realization led me to explore other possibilities.

At my age, I no longer need a large, fancy SUV. I started looking for a smaller SUV with an attractive financing package, starting at 1.9% interest. That way, I could save money and enjoy the peace of mind of a manufacturer’s warranty. After all, this is the kind of practical thinking I have always recommended to my mortgage clients!

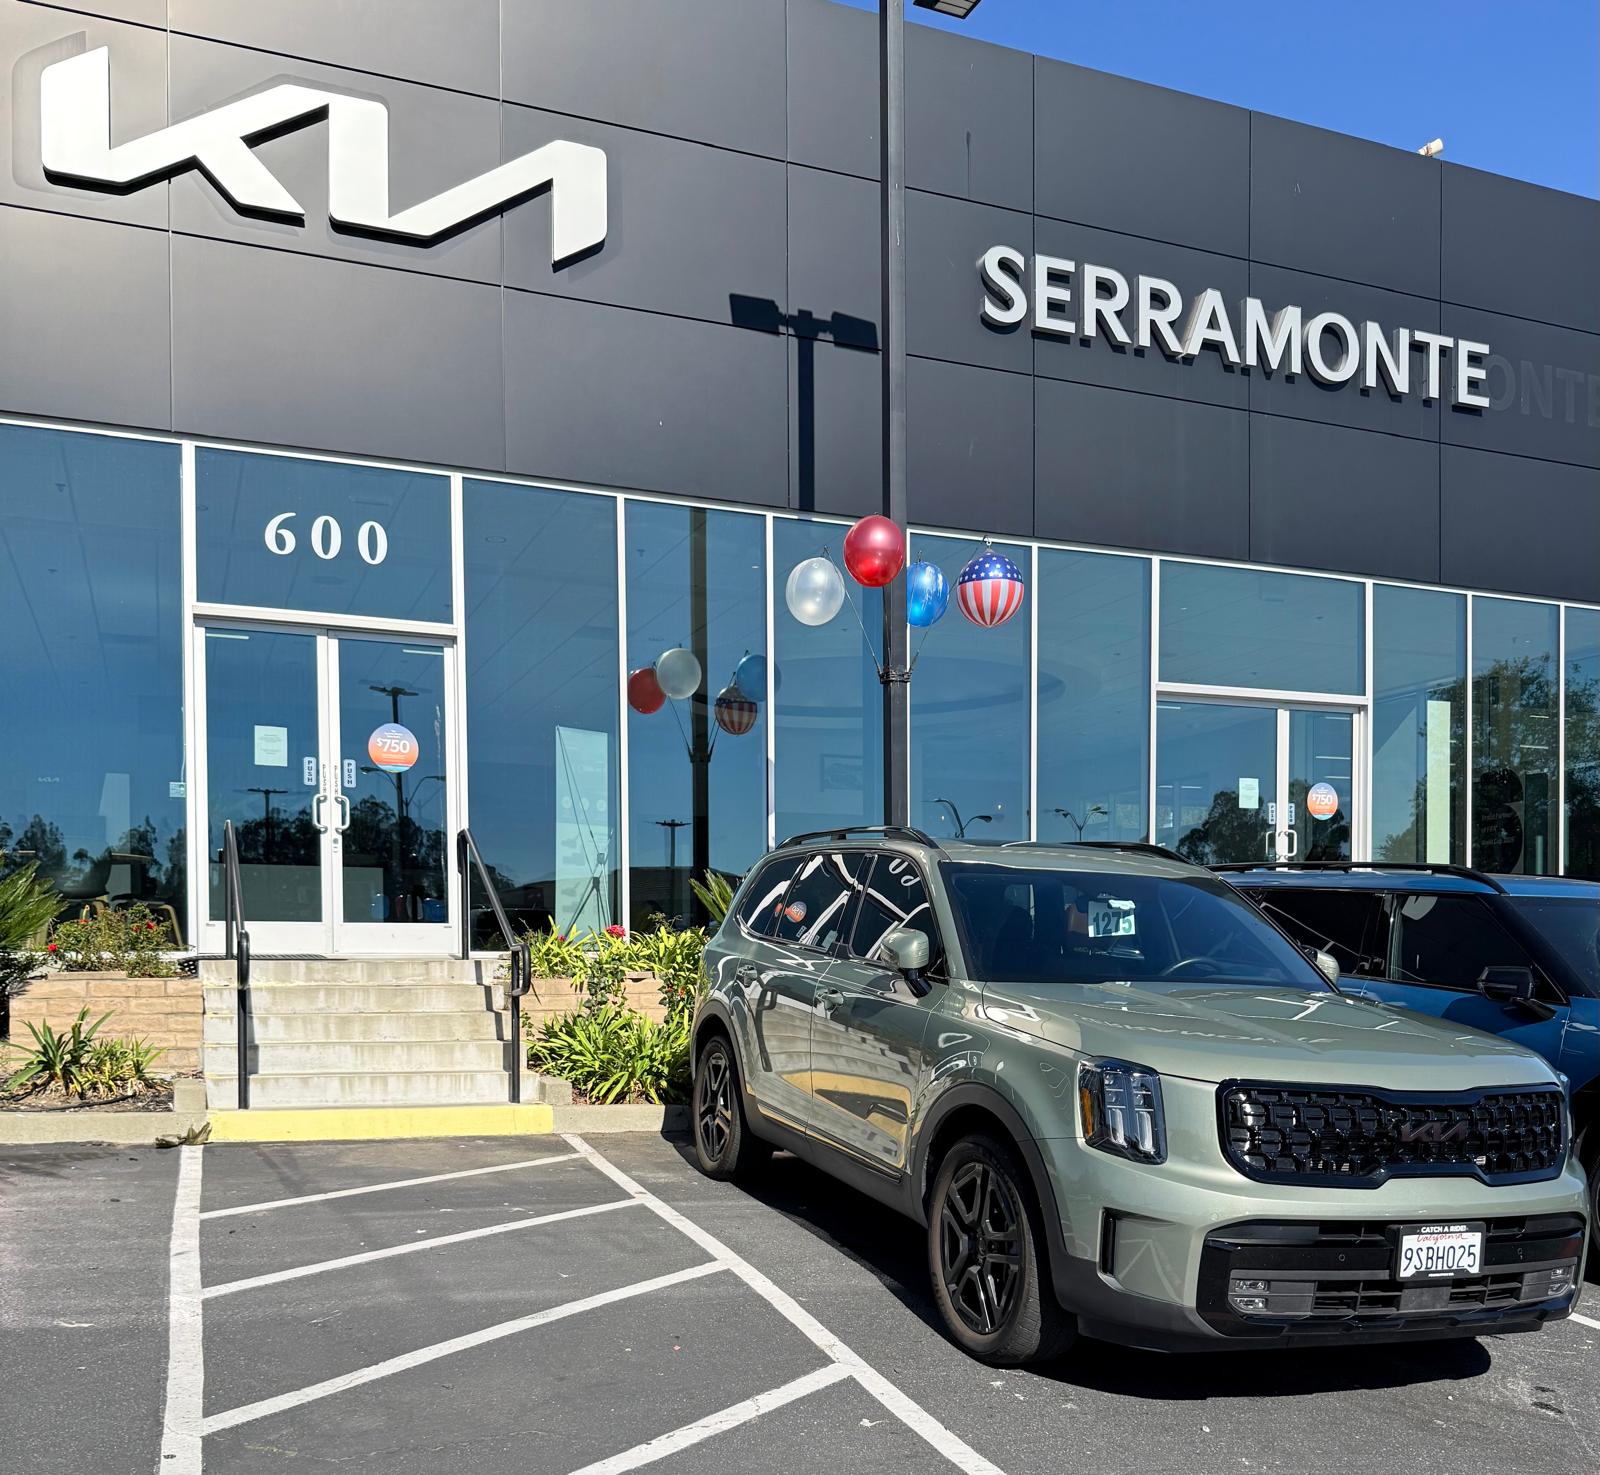
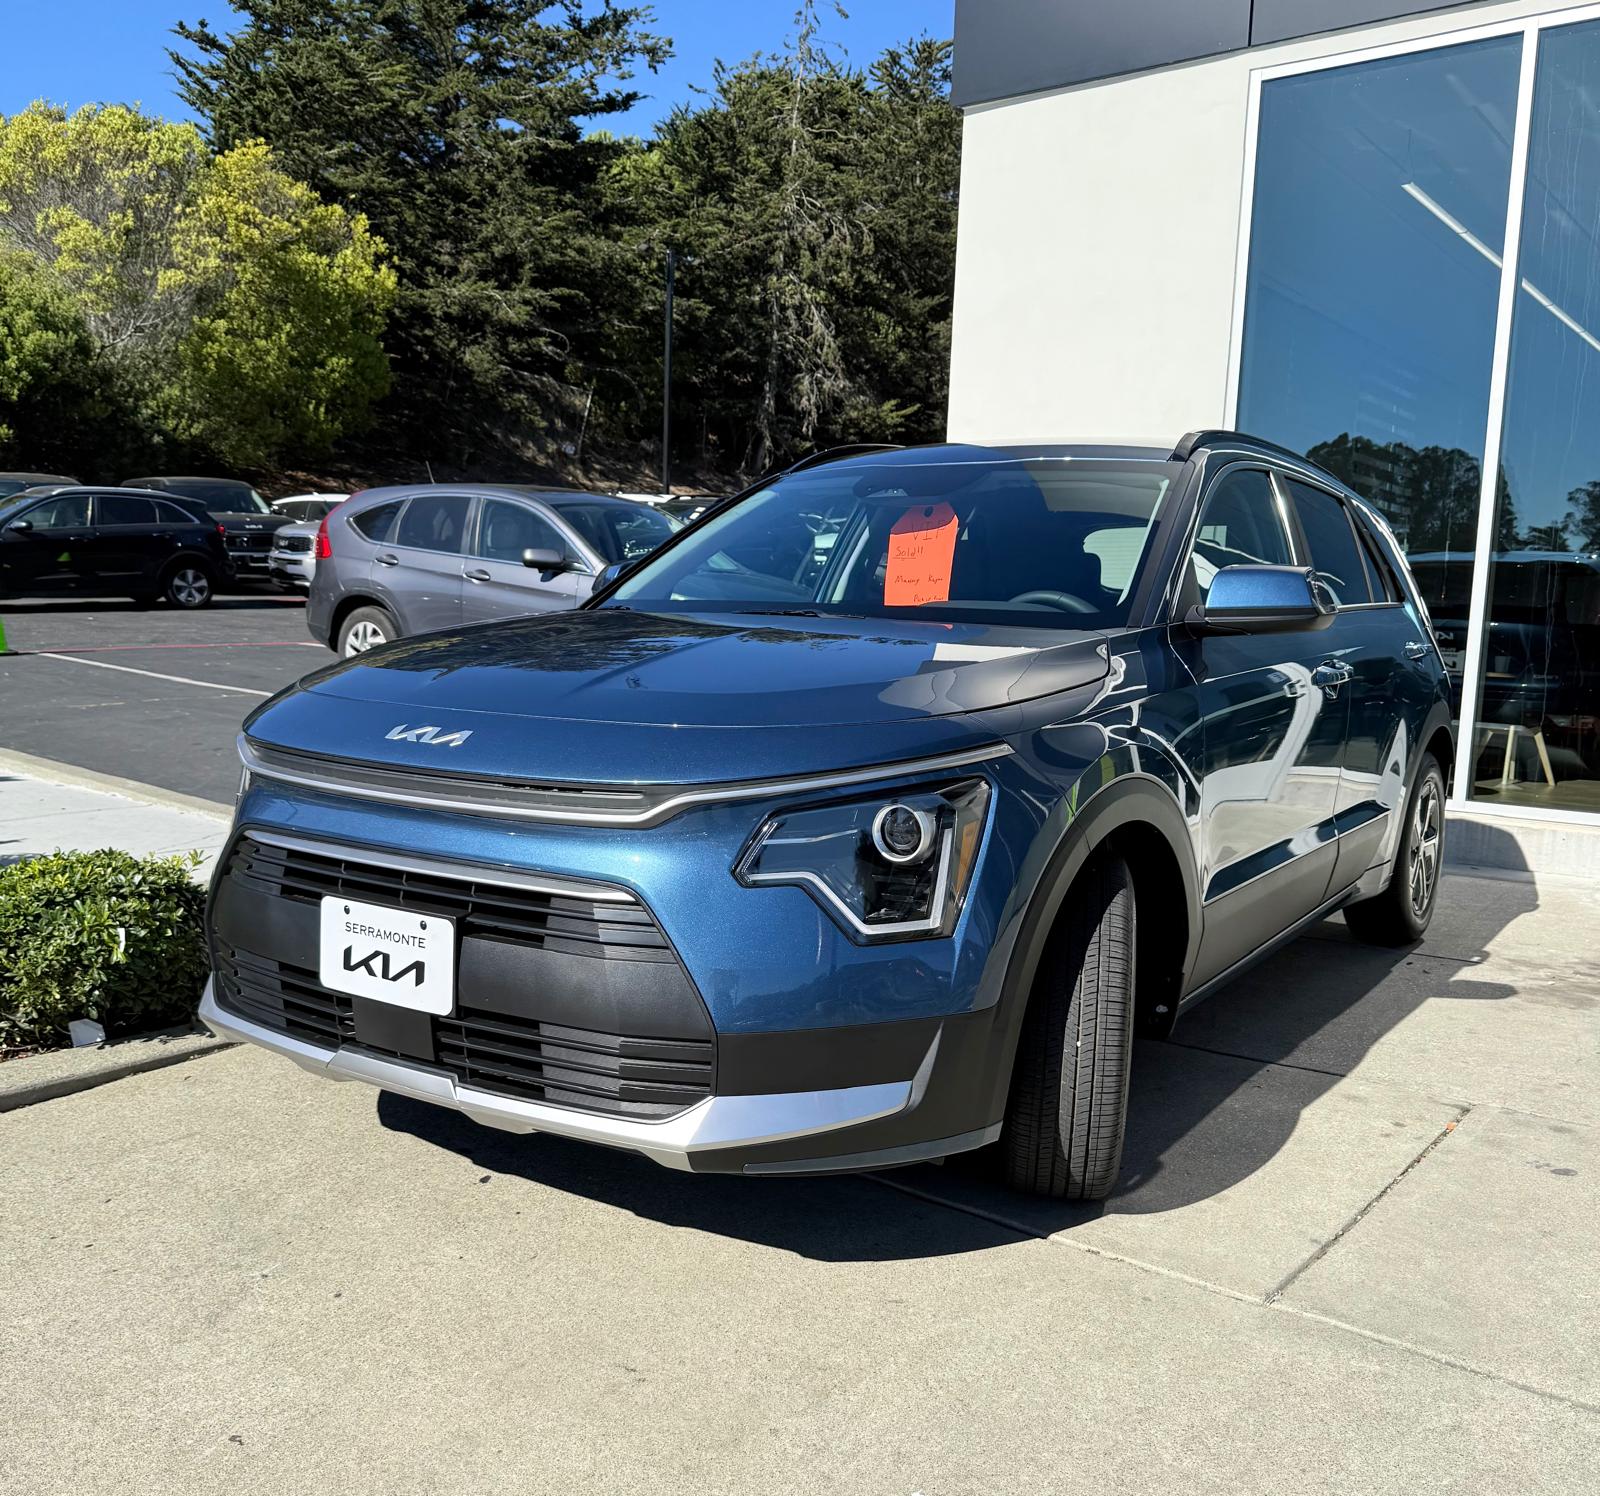
Not far from our office is a Kia dealership in Serramonte along with other dealerships in the area. I decided to take a look. When I entered the showroom, I saw a beautiful blue car with a sticker advertising 54 miles per gallon. It turned out to be a hybrid, which was exactly what I was looking for! It offered excellent fuel economy and required only regular 87-octane gasoline instead of the more expensive 92-octane fuel I use now. Since my wife already has an electric Smart car, getting another fully electric vehicle didn’t make much sense for us.

A hybrid seemed to be the perfect compromise. I looked at several beautiful cars in different colors, but blue is my favorite, so that made the decision easier. The car also came with an attractive financing package at 1.9%.

There is an old story about Henry Ford and the Model T. According to the famous saying, customers could have any color they wanted, as long as it was black. In fact, the Model T was available in several colors between 1908 and 1914 before Ford eventually standardized on black for production-efficiency reasons.

Fortunately, we have come a long way since then! Today, we can choose from all kinds of beautiful colors. And here is another interesting observation: despite what many people believe, red cars are not necessarily the most likely to attract a police officer’s attention. White cars are often reported as being among the most frequently stopped, although the number of cars of each color on the road also matters.

After choosing my new car, I agreed to leave it at the dealership and return later to pick it up. When I came back, I noticed a sign on the windshield. It said: VIP Manny Kagan SOLD. That was a nice way to welcome me back!

So, if you decide to follow my lead and visit the Kia dealership in Serramonte, ask for the same VIP treatment and a good financing deal. You can also ask for the manager, Ebrahim Rahimi.

I promised you a good story, and I hope you will enjoy the ride! Three images above show only some of the available colors.

Enjoy and share!

image

The Good News with Manny

Dear friends,

Today, I received some exciting news, and I decided not to wait until Wednesday, when I usually share Good News with Manny. So, consider this a bonus edition!

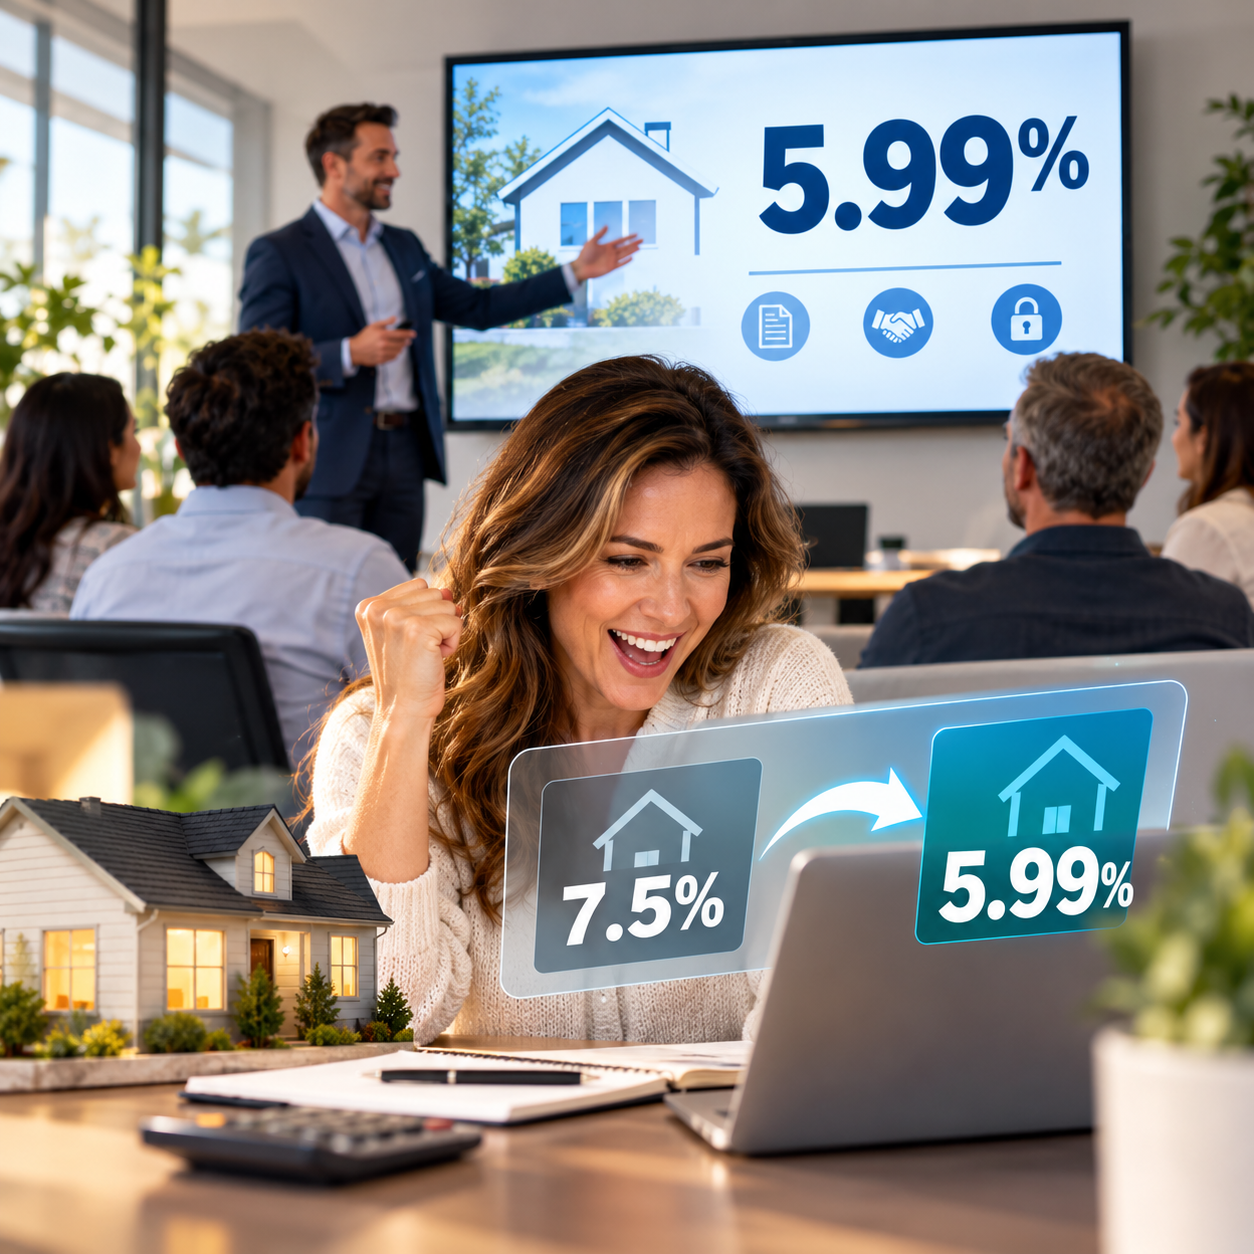
Today, we had a presentation at our office from a lender offering home equity lines of credit with fixed interest rates starting at 5.99%. What makes this program especially interesting is that qualifying may be easier than it is for many other loan products.

I got so excited about this opportunity that I decided to explore refinancing the second loan on my own home, which currently carries an interest rate of 7.5%! I’ll keep you posted on how it goes.

Meanwhile, this program may not be right for you, but perhaps you know someone who could benefit from it. Maybe they want to pay off other debts, consolidate credit card balances, or access funds for a project they have been planning.

If you or someone you know is interested, please reach out to me. I’ll be happy to provide more details, explain the costs, and explore whether this opportunity makes sense for you. Your home equity may be a valuable resource. Let’s explore how you can put it to work for you!

Warm regards,

Manny Kagan
Mortgage Broker | 40+ Years of Experience
(415) 225-7920
Fridays with Manny

image

We Don’t Take Pictures.
We Create Images.

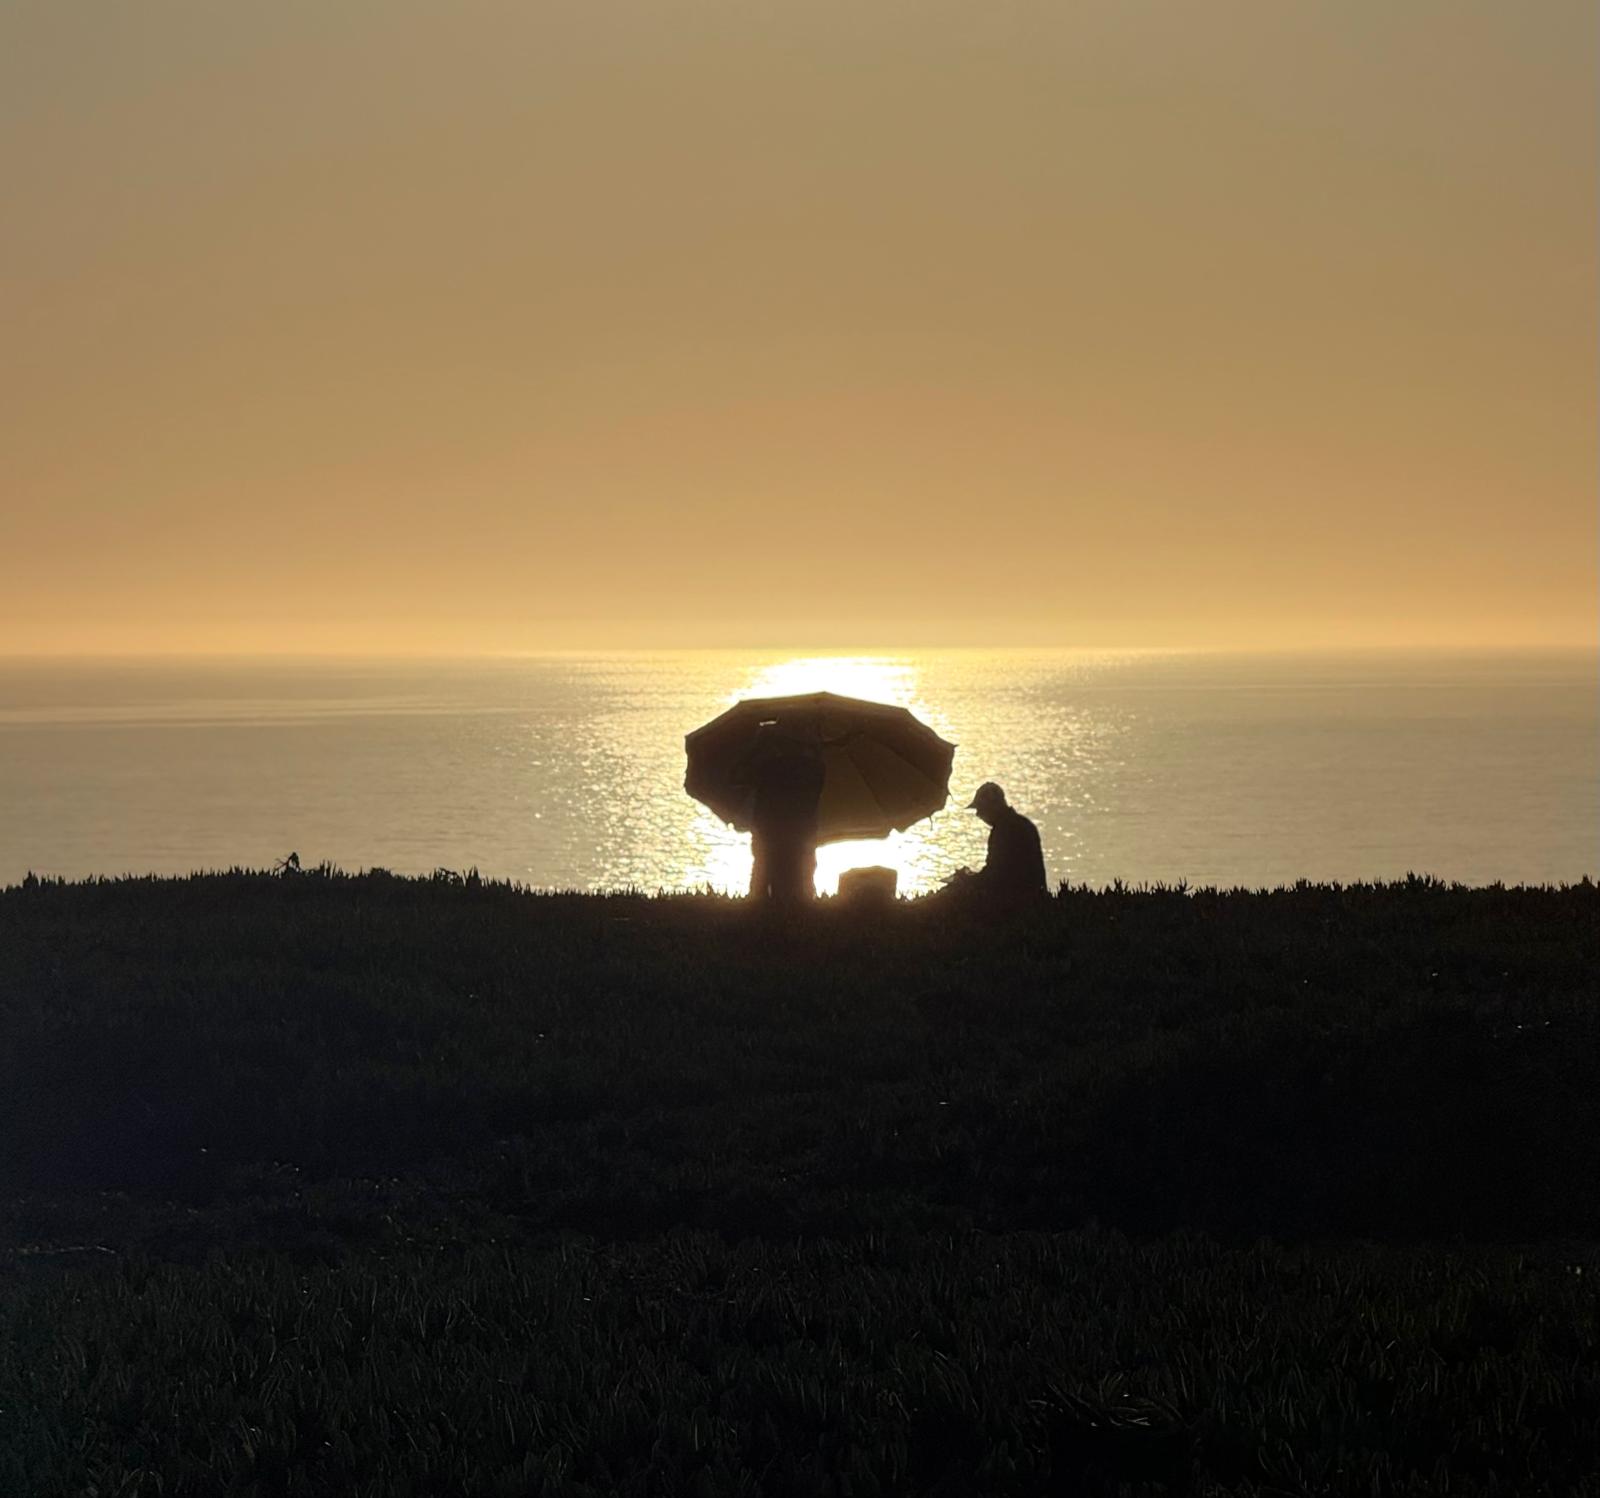
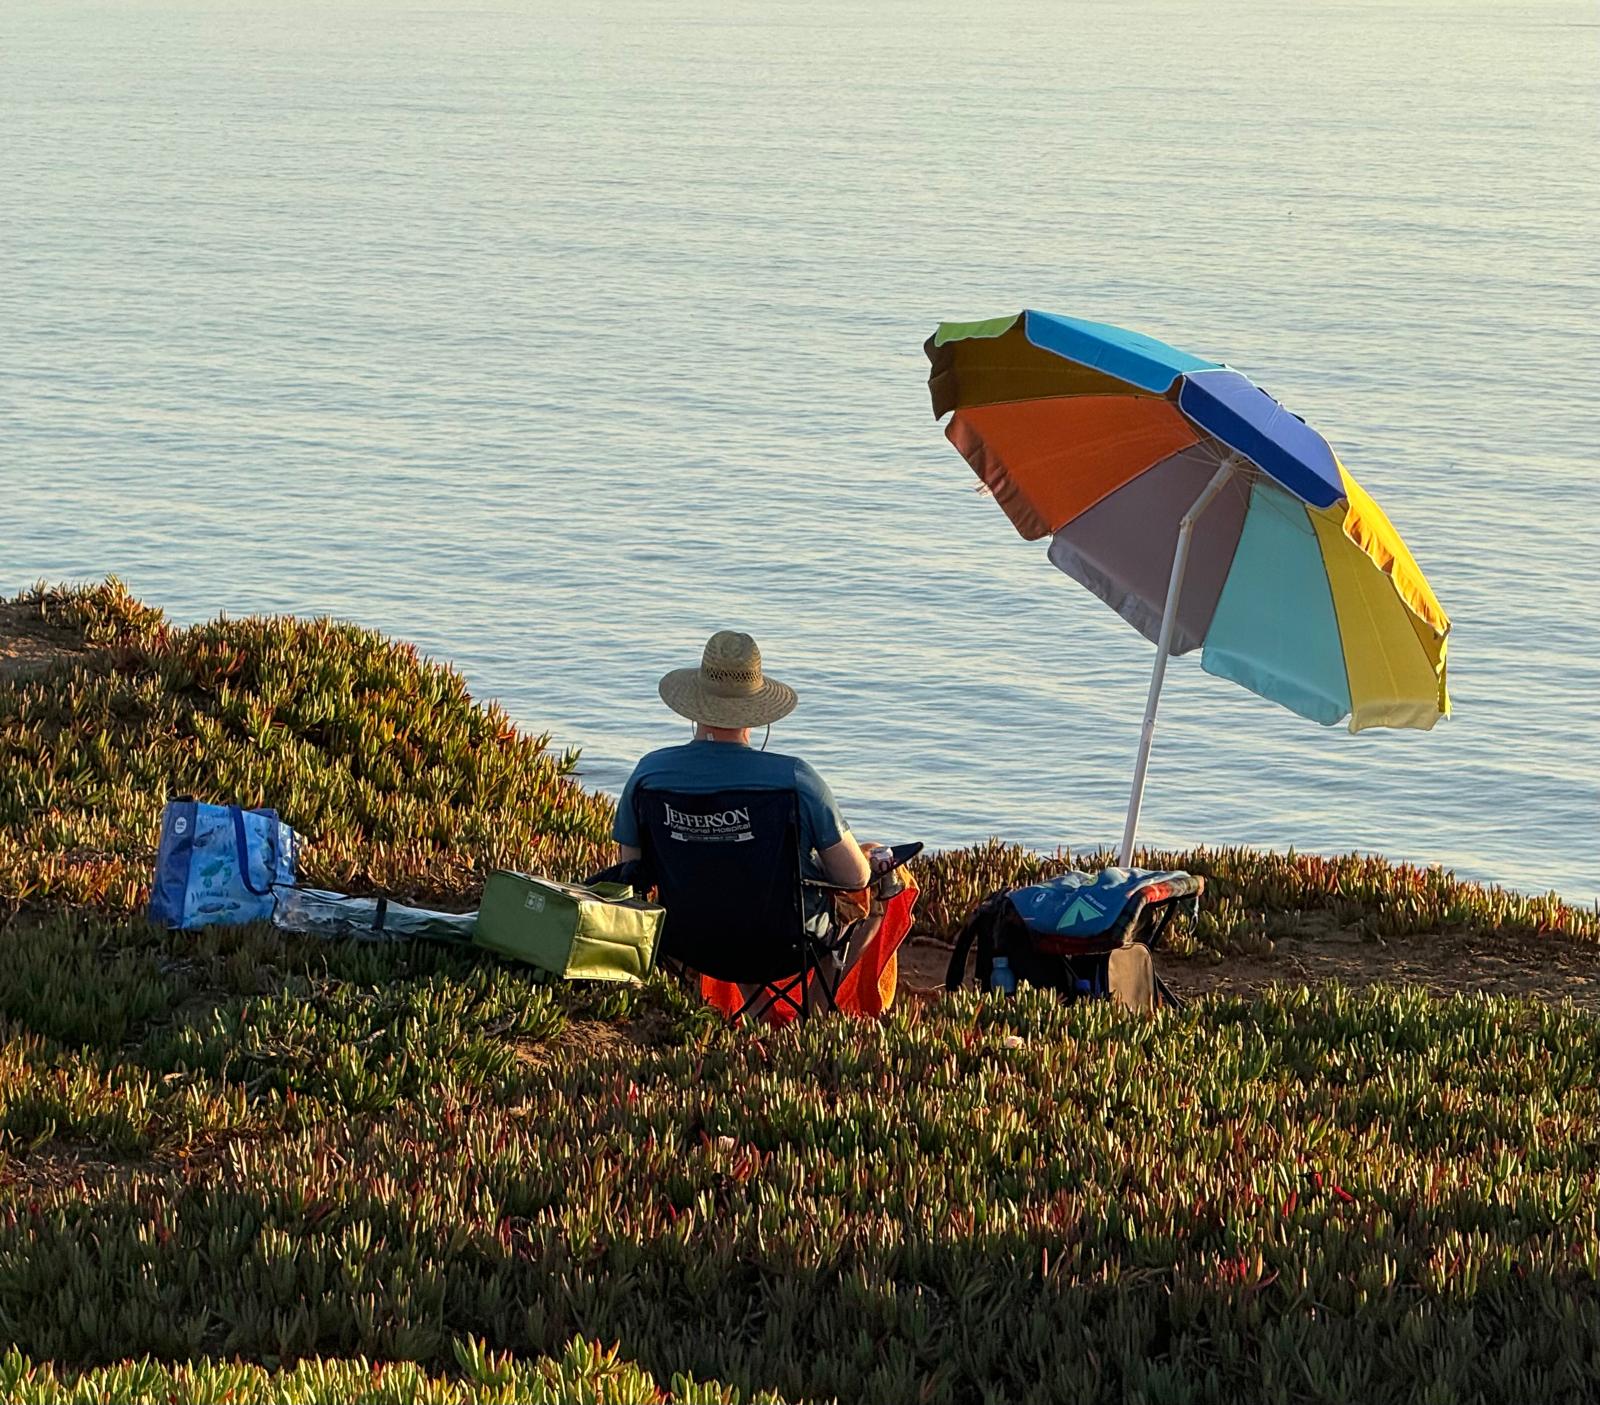
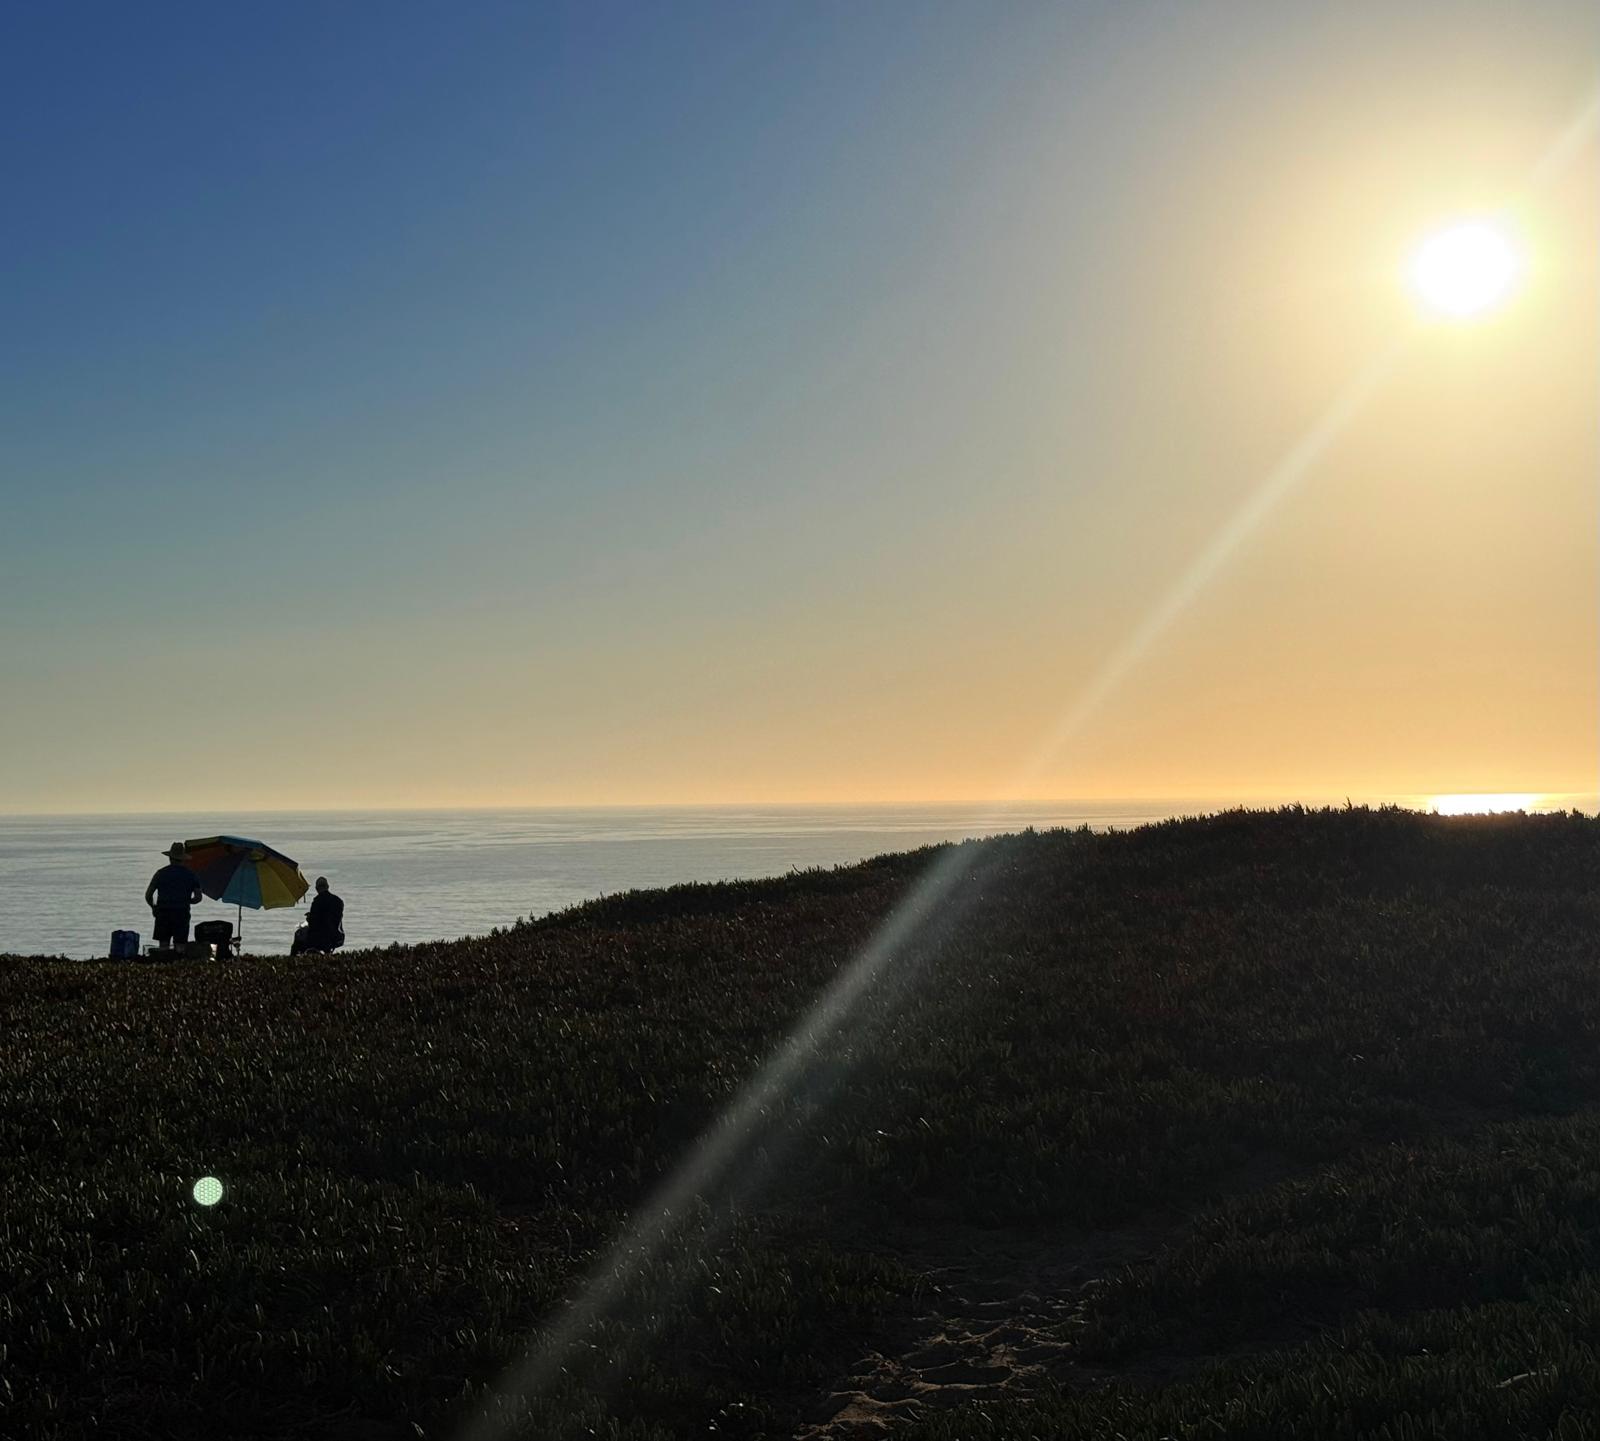
The idea for this story came to me during our Sunday afternoon walk at Fort Funston. Our Labradoodle Max loves coming here because he can run freely without a leash. We love it because we can watch the sunset, enjoy the ocean, and see so many people walking with their dogs. And, of course, I photograph all the time. After looking at one of the pictures I took that day, I realized that making a picture like this requires a certain skill.

I have studied photography for many years. I have taken courses, read books, and looked at thousands of great photographs by great photographers. I am confident that I am a good photographer. I have even published four books of my photographs. But when I see somebody else’s picture—just a quick snap—I often don’t even know how to explain to the person what could make it a better image.

In my mind, we are not taking photographs. We are making images. I call myself an artist, not a photographer. When I see something, I try to see the image in my mind before I press the button. Then, after I take the photograph, I may crop it—often into a square—and that becomes part of the creative process.

The three images I am sharing with this story are a good example. They were all created from essentially the same spot and the same subject. In one, there is an umbrella and a person standing on the beach—or perhaps on top of the cliff—with the sunset behind them. In another, from almost the same place, I noticed two pelicans flying by and created a completely different image. Same place. Similar subject. Different images. So how do you make a good photograph? I think there are a few simple rules.

First, you have to see the result before you take the picture. This is probably the most difficult part. You have to develop the ability to visualize what the final image could look like. Second, you have to see the light. Where is it coming from? What is it illuminating? What is it hiding? How does the light change the feeling of the picture? Third, you have to see the subject. What is it that you want to say? What caught your attention? What do you want the person looking at your image to feel? And finally, you have to compose. Composition means deciding where everything belongs in the picture so that the final image looks the way you imagined it.

It is easy to say. It is much harder to do. I believe the only way to develop this ability is through practice—taking many pictures, looking at them afterward, asking yourself what worked and what didn’t, and trying again.

Can you learn this skill? Absolutely. But why would you want to? Most of us simply take pictures because we want to remember where we were or what we saw. We take pictures like tourists. But some of us want something different. We don’t just want to record what we saw. We want to create what we saw in our mind.

That is why I am sharing these images with you. They were all created from the same place, looking at almost the same scene, but each one tells a slightly different story.

I hope you enjoy them. And if you do, share them with a friend.

image