A SIGH OF RELIEF
Part Two
Last week, I shared some of the challenges I faced while helping a client obtain a mortgage so she could pay her sister her share of their father’s inheritance. We had already overcome several obstacles, but the real kicker was still ahead.
After finding a way to obtain a smaller loan, I had to find a way to get my client a much larger amount of money. We needed a loan program that would not require her to provide tax returns. Fortunately, my client had just turned 62. That opened another possibility: a reverse mortgage.
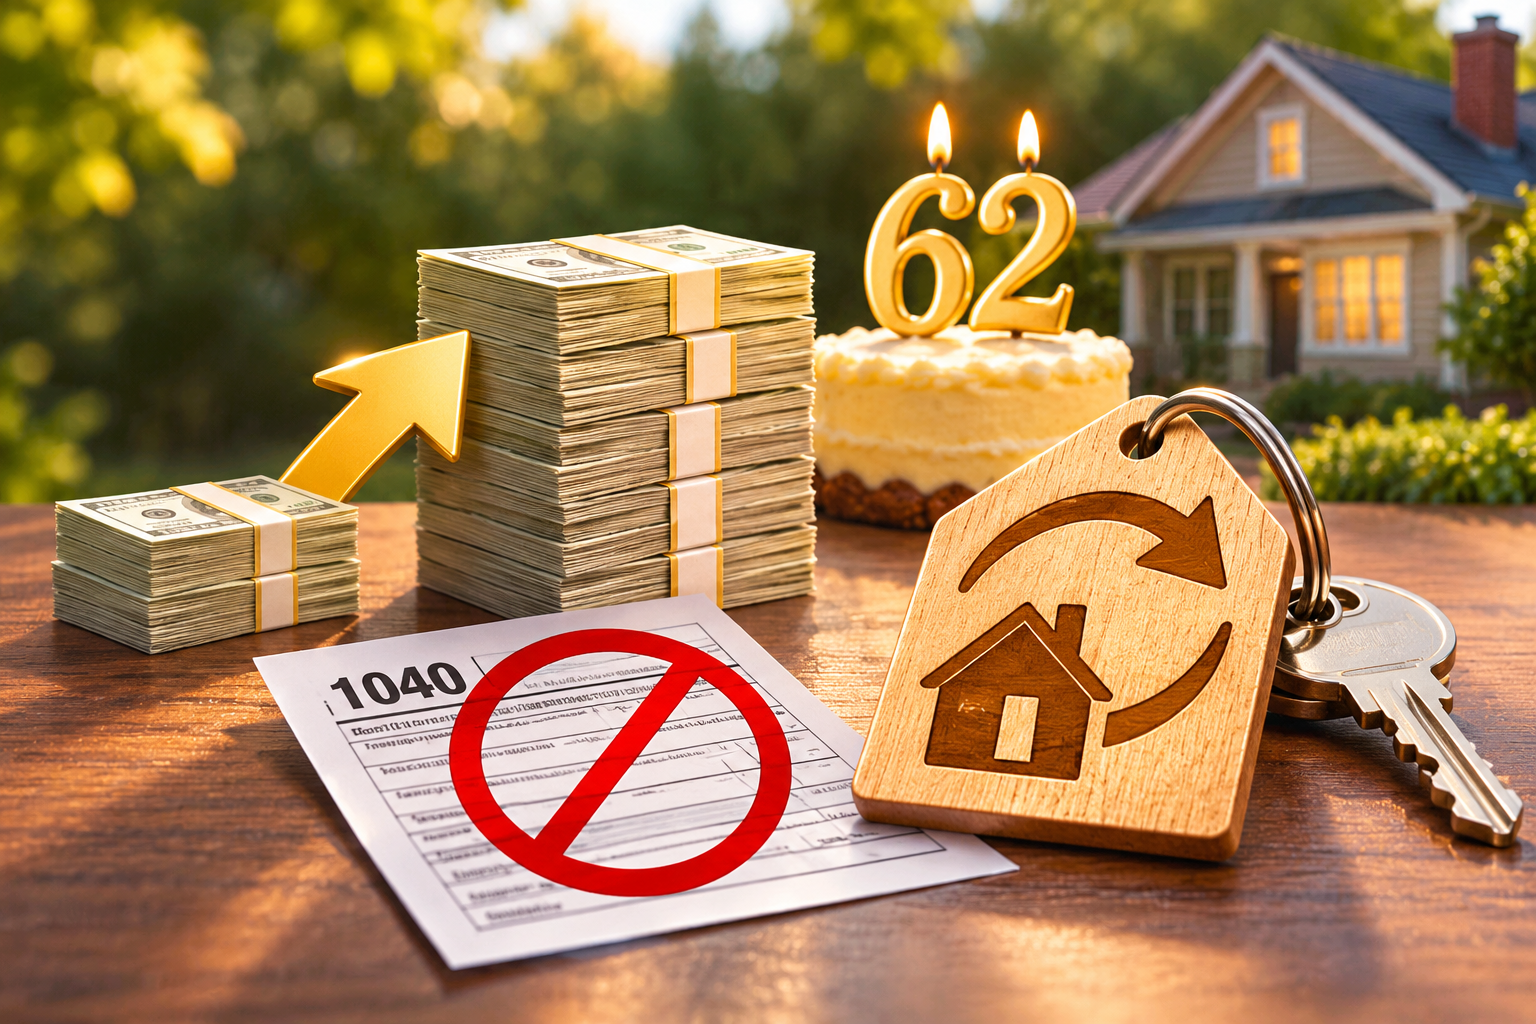
Reverse mortgages are available to eligible borrowers starting at age 55 under some programs, although the age requirements depend on the type of loan. With reverse mortgages, the older the borrower, the more money may be available, subject to the property’s value and other requirements.
Because the property had a high value, we needed two appraisal reports. The results were surprising. One appraisal showed a much higher value than the other. Unfortunately, the lender had to use the lower of the two values. Fortunately, even the lower value gave us enough equity to obtain the money my client needed. I thought we were finally getting close.
Then another unexpected condition appeared. My client’s credit score was around 680, and the lender required tax returns. But my client hadn’t filed them. I had never encountered this particular situation before. So, I decided to submit the loan to another lender.
There is a saying often attributed to Albert Einstein that the definition of insanity is doing the same thing over and over again and expecting different results. Perhaps I was doing exactly that. But the new lender looked at the situation differently.
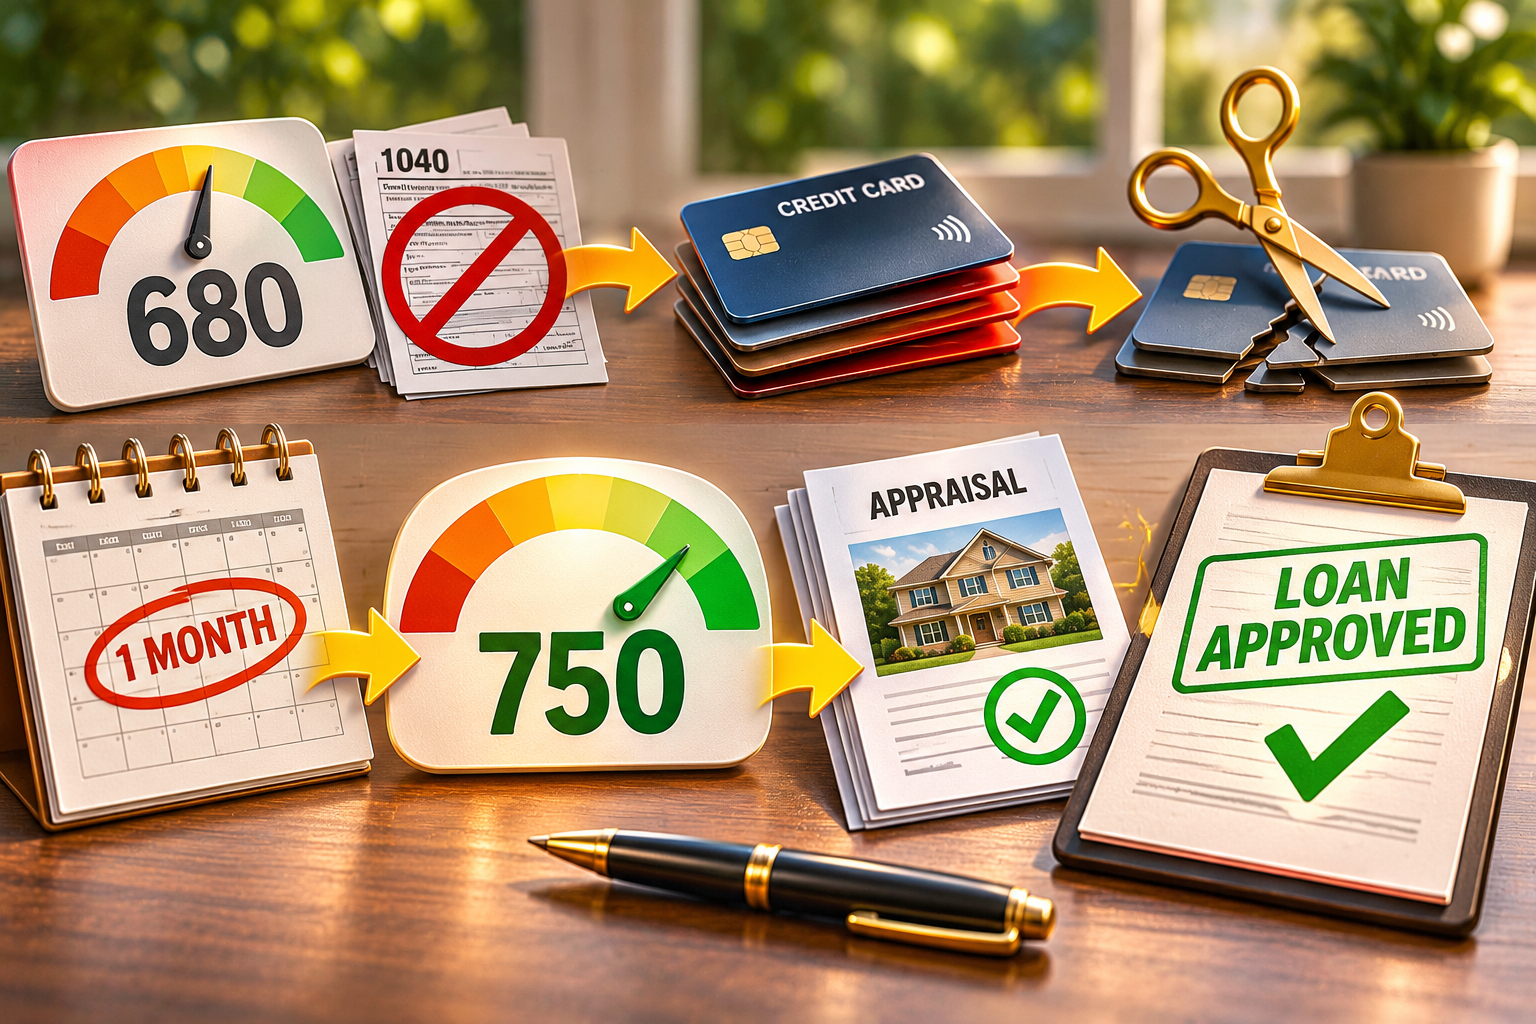
The lender told me that if we could get my client’s credit score to 720 or higher, tax returns would not be required under that particular loan program. Now we had another possible solution. I suggested that my client use some of the money she had received from the first refinancing to pay off her credit card balances. She did.
About a month later, we checked her credit again. Her score had increased to 750. That changed everything. We were able to transfer the appraisal reports to the new lender, and the loan was approved.
Of course, we still had some title-related issues to resolve, and we were running out of time. But we kept going. Finally, last week, I received my commission check. My wife, Elpha, and I have worked together for more than 40 years. When she saw the check, she said something that made me smile: “Now you can say that the deal is closed.” And she was right. What a relief!
Looking back, this double transaction taught me something important. When you begin working on a complicated mortgage, you cannot predict every obstacle you will encounter. Sometimes, you don’t discover a problem until you have completed several steps.
And sometimes, a solution that seems impossible at first becomes possible when you look at the situation from a different angle.
- You have to be patient.
- You have to know your options.
- And you have to be willing to keep looking when the first answer is no.
This is true in the mortgage business, and I believe it is true in life. After more than 40 years in the mortgage business, I still learn something from every complicated transaction. And that is one reason I enjoy what I do.
There are many people out there who are struggling with financial problems and don’t know where to turn. Some may need help with a mortgage. Others may need someone to explain their options and help them understand what is possible.
So please don’t be shy about reaching out to people who might need help. Sometimes, all it takes is a conversation to discover a possibility they didn’t know existed. Where there is a will, there is a way.
Thank you for following my story!
Manny Kagan
Mortgage Broker | 40+ Years of Experience
(415) 225-7920