HOW TO REMOVE AN EX-HUSBAND’S NAME FROM THE TITLE
I received a phone call from a woman who told me that she had been referred to me by her financial planner. As soon as she told me who the financial planner was, I had a pretty good idea what kind of case this would be, because her planner is specialized in helping women who were going through divorce.
This time the situation seemed simple. The client and her husband owned two properties. They had decided to sell one of them. The other was a condominium where she lived with her mother, and she wanted to keep it. There was only one problem. Her husband’s name was on the title, along with her mother’s and her own name. She wanted to keep the condominium, and to remove her husband’s and mother’s name from the title. To do that, we need to refinance their existing mortgage.
The question was: Could she qualify for the mortgage by herself? Normally, the first thing I look at is income. In her case, there wasn’t much conventional income. Her main source of income was from helping and caring for her elderly mother.
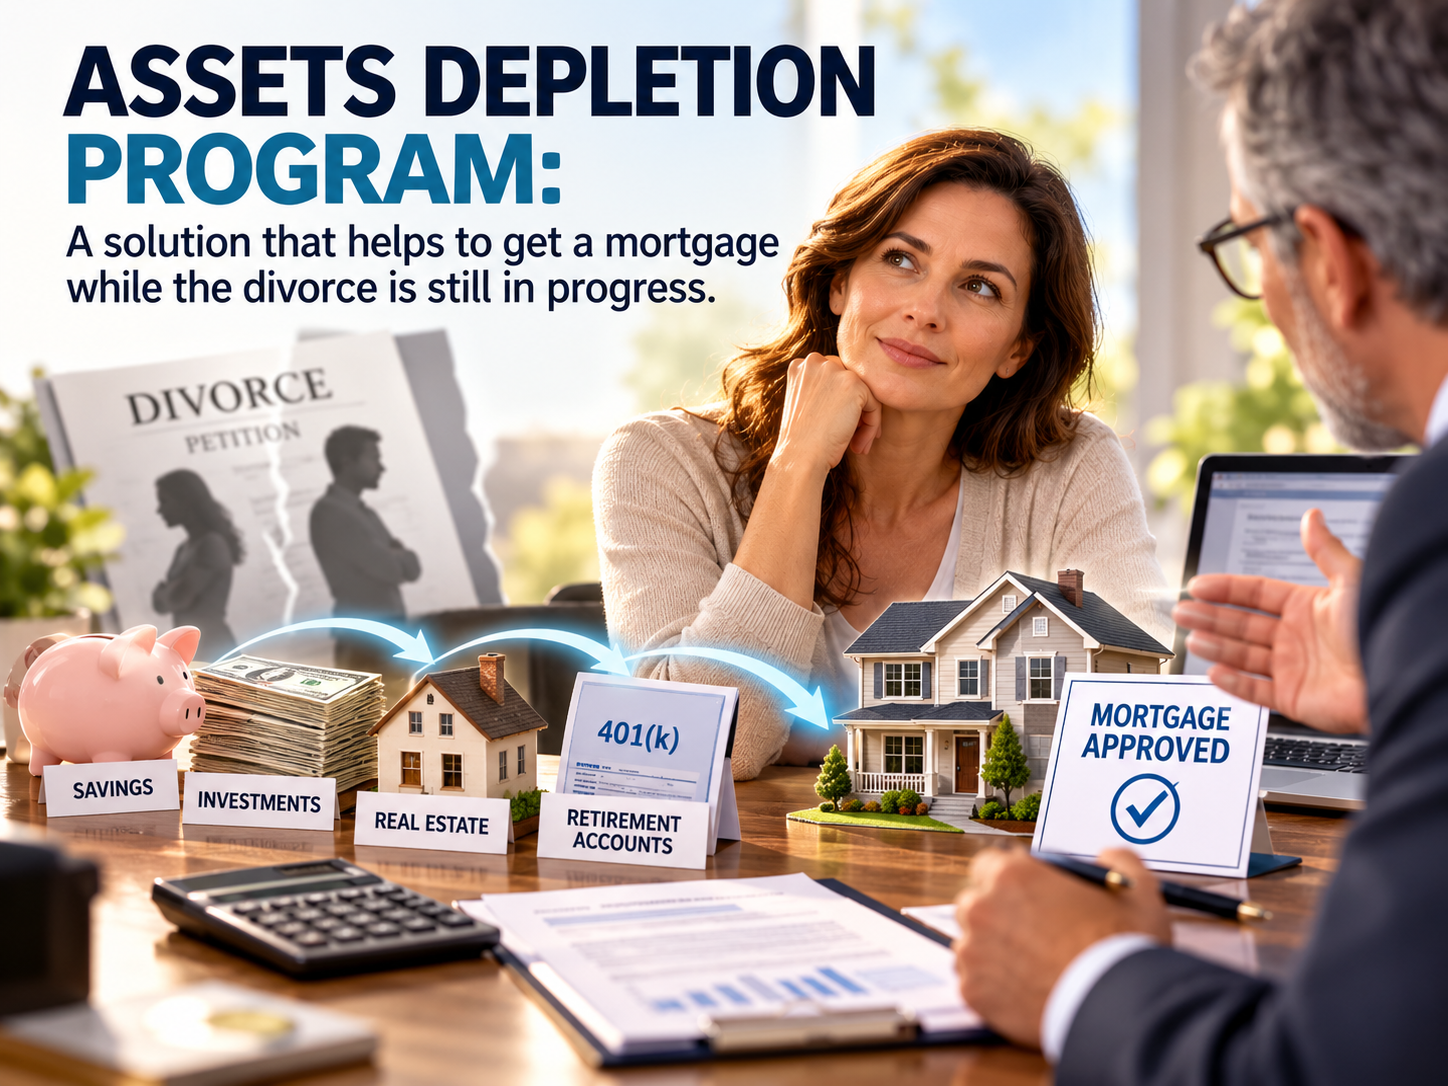
At first, it looked like a challenge. But then I learned something important. Over the years, she had accumulated and saved money in retirement accounts. When we looked at the numbers, she had more than $1 million in her IRA accounts. She didn’t have a large conventional income, but she had substantial assets. That changed the picture.
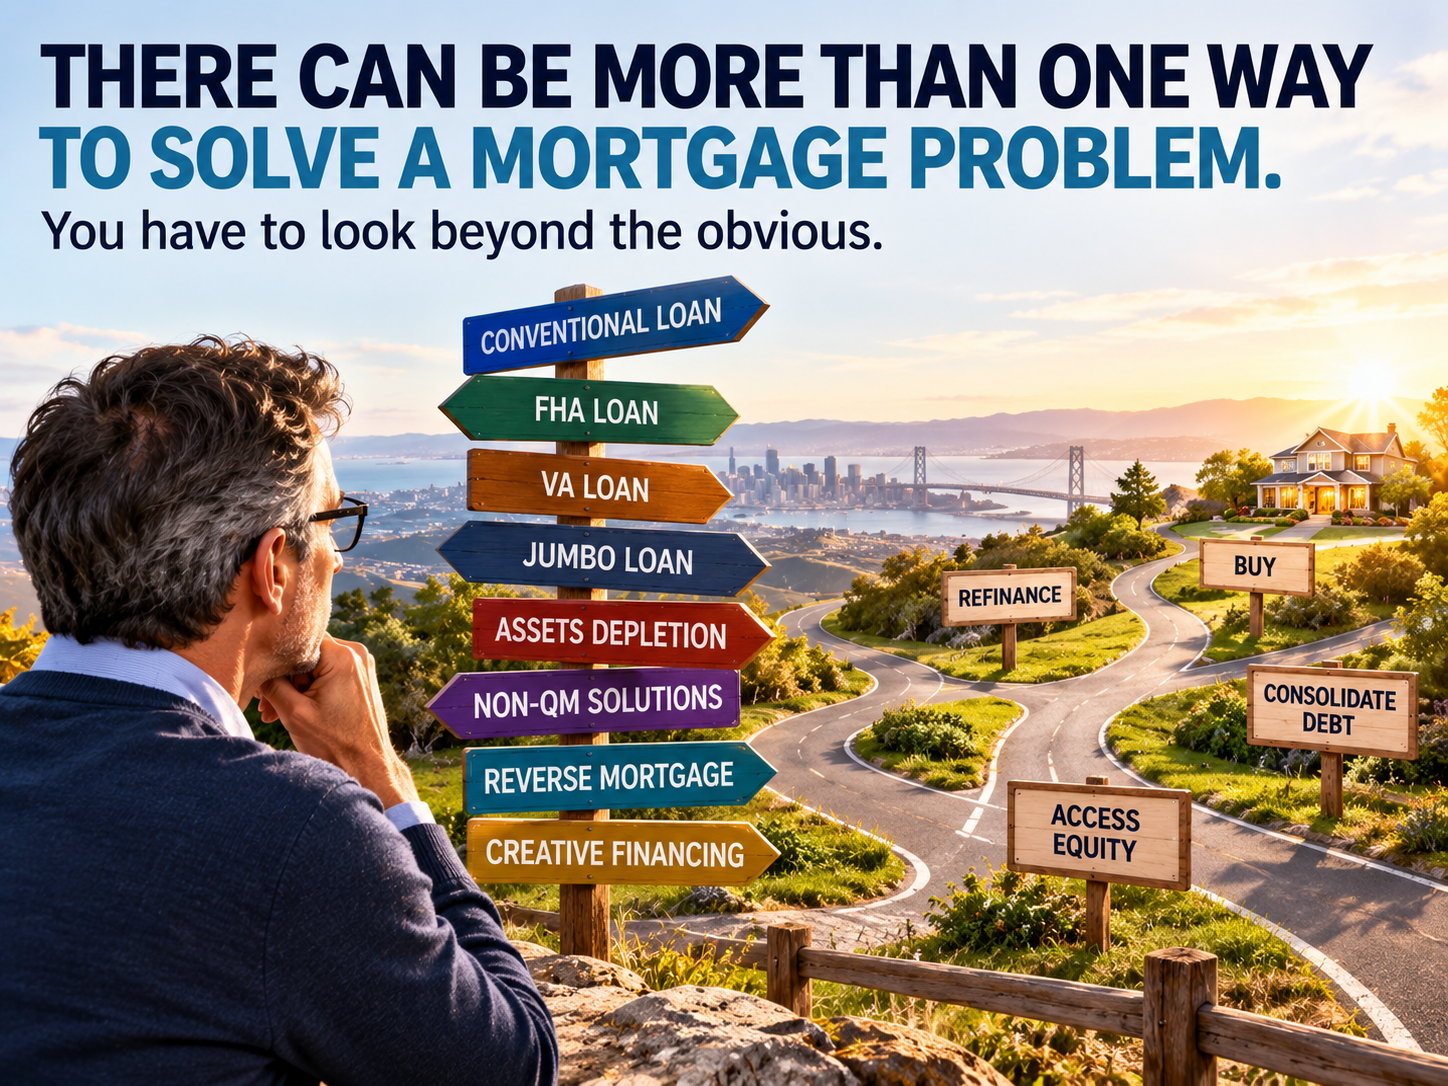
I was able to use a program that allowed qualifying income to be calculated from her assets. It is sometimes called an Assets depletion program, because the lender calculates a qualifying income amount by treating a portion of eligible assets as if they were being used over a specified period of time. That gave us enough qualifying income for her to obtain the mortgage she needed. She could keep the condominium under her own name. And she could do it while the divorce was still in progress.
This was not something I learned from a textbook. I learned many of these tricks of the trade during more than 20 years of working closely with a divorce attorney who specialized in helping people reach amicable divorces. Over the years, I learned that when people are going through a divorce, the problem is not always simply, “Who gets the house?” Sometimes the real question is: How can we structure the financing so that the person who wants to keep the house can actually afford to keep it?
There can be more than one way to solve a mortgage problem. You have to look beyond the obvious. In this case, her income was not enough by itself. But her assets told a different story. And that was the key to finding the solution.
If you’re planning to get a mortgage and want to know whether your loan can actually be done, give me a call. I know how to help.
Manny Kagan
Mortgage Broker | 40+ Years of Experience
(415) 225-7930